Revolut, the global fintech, has announced the incorporation of Revolut Ventures in collaboration with Carne Group, Europe’s largest third-party management company.As explained, Revolut Ventures will serve as a bridge between selected investors and high-growth, unlisted technology companies.
The company explains that these businesses are taking increasingly longer to go public, with the median time rising from 6.9 years in 2014 to 11 years in 2025. Consequently, a large portion of value creation now takes place prior to an IPO. In their view, these investment opportunities have traditionally been reserved for large institutions and high-net-worth individuals, leaving retail investors on the sidelines. In parallel, the firm maintains that public equity investment opportunities in the U.S. have been cut in half, dropping from 7,000 listed companies in 2000 to 3,900 in 2025. “More and more mature, cash-generating companies are becoming privately held or deciding never to go public, reducing opportunities for retail investors,” they point out.
As one of the world’s leading privately held tech companies, Revolut has deep, first-hand knowledge of the private markets ecosystem. The creation of Revolut Ventures represents a natural evolution following the launch of Private Markets in July 2026 across selected EEA markets.
Through partnerships with some of the world’s most prominent unlisted technology companies, the Revolut Ventures platform will be integrated into the Revolut app alongside existing investment options, which include U.S. and EEA stocks, ETFs, money market funds, bonds, and private market funds. While these alternatives offer growth potential, they are significantly less liquid than publicly traded equities and carry a substantial risk of capital loss.
Rolandas Juteika, Head of Wealth and Trading (EEA) at Revolut, stated that “with Revolut Ventures, our goal is to break down one of the final barriers in wealth management: the exclusion of retail investors from unlisted companies. Value creation occurs long before an IPO, and by operating our own platform, we are giving everyday investors the opportunity to access tomorrow’s market leaders directly from the Revolut app.”
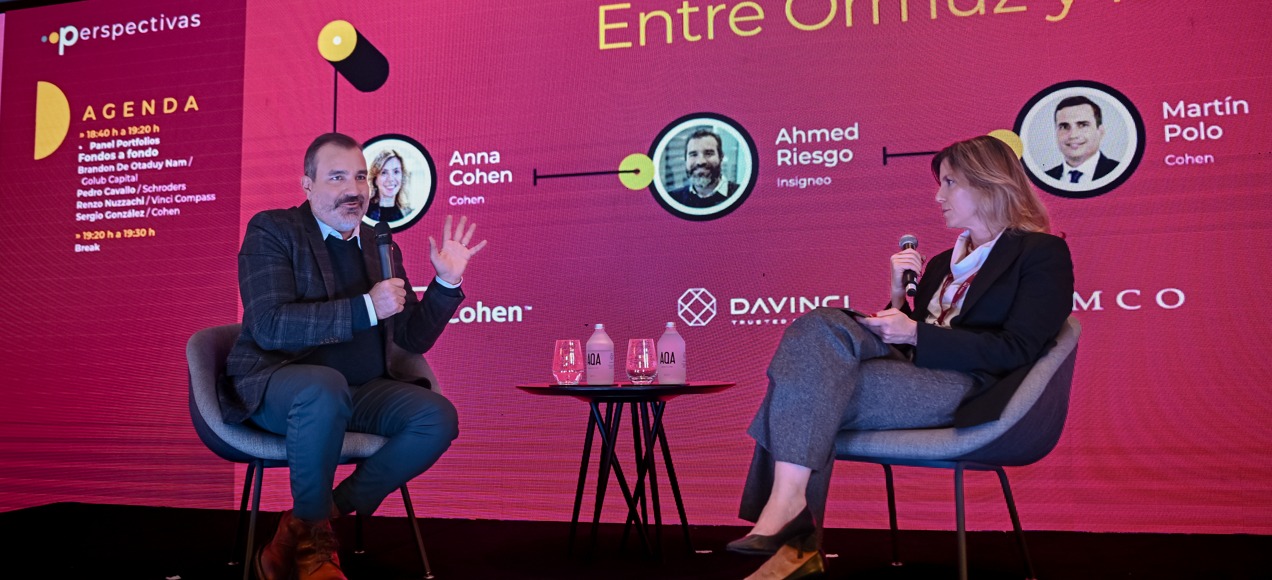
Republicans are projected to lose control of the Senate in the U.S. midterm elections on November 3, 2026. This was anticipated by Ahmed Riesgo, Chief Investment Officer (CIO) of Insigneo, during the webinar “Brazil and the U.S.: Two Decisions, One Market,” organized by Grupo Cohen and moderated by its President and CEO, Anna Cohen. Riesgo attributed this scenario to Donald Trump’s unpopularity, the inflationary impact of tariffs, and public opposition to the war with Iran. For the executive, the surprise would not be an administration defeat, but rather Republicans managing to retain the upper house.
According to Riesgo, Republican states that seemed safe six months ago—Iowa and Texas, among others—are now open contests. Riesgo highlighted the case of Texas, where Democrat James Talarico could defeat Ken Paxton. “Texas voting Democratic blue has very few precedents in history,” Cohen noted. Riesgo clarified that the phenomenon does not reflect an ideological shift, but rather direct punishment of the president for rising prices. “You see it in the polls. They are going to crucify him over the war, and they are crucifying him,” he stated.
The Argentine analyst underscored the convergence of factors impacting the electorate: “You have a trifecta of negative impacts: the pump and consumption, the rate hike and borrowing costs, and the entire social issue, which in the United States continues along polarized trends.” Riesgo agreed: the political thermometer of the average American is the price of gasoline, and when it rises, the government pays the price at the ballot box.
The War with Iran
Riesgo highlighted the weak support for the intervention in Iran. A Pew Research Center survey conducted March 16–22, 2026, found that 59% of U.S. adults considered the initial decision to use military force a mistake, while 38% considered it correct. However, the executive cautioned that it would be premature to judge its long-term consequences. “There are signs that it could have positive long-term benefits, both for the United States and for the region, which are not visible today,” he added.
According to Riesgo, the combination of the military conflict and trade tariffs puts upward pressure on energy and input costs, and their eventual pass-through to consumers would deepen discontent among lower-income households. Cohen noted that higher-net-worth Americans are partially shielded: “Consumption has not fallen. Savings probably have; they are not over-leveraging, but there is some form of friction regarding inflation.”
The Insigneo CIO also commended the Trump administration’s push for artificial intelligence. In his estimate, the new technology lifts the economy’s potential growth from a baseline of 1.8% to nearly 3%. This is an estimate by the executive, not observed data or an official consensus. “It doesn’t sound like much, from two to three, but a shift in the trend level of growth for an economy the size of the United States is, as Trump says, ‘huge,'” he illustrated.
The strategist drew a parallel with Robert Solow’s 1987 paradox regarding the difficulty of seeing the impact of computers in productivity statistics. In Riesgo’s view, corporate margin expansion reflects AI benefits that those metrics do not yet capture. “Where did it come from? Did it come from Americans suddenly wanting to work harder? No, it’s the opposite. Every day Americans want to work less,” he quipped.
Cohen summarized the tension with a direct question: “What happens if there is a scare with upcoming earnings reports? Where does the S&P end up?” Riesgo replied that while some companies—particularly those exclusively exposed to frontier AI models—need extraordinary growth to justify their valuations, the vast majority of sectors are still pricing in very few benefits from the new technology.
Riesgo Projects the 10-Year Bond at 4.80% by Year-End 2026
Faced with a futures curve projecting policy rate increases in December 2026 and in March and September 2027, Riesgo deemed that monetary tightening excessive. The specialist stressed that the Federal Reserve is unlikely to follow that path and recommended positioning in duration: “One of the easiest trades to make money on in my career has been betting that the central bank is not going to do what it is telling you it will do,” he argued. Along those lines, he set his year-end target for the 10-year Treasury at 4.8%, 16 basis points below the 4.96% recorded by the benchmark note following trading on October 22.
During its quarterly client presentation in the final week of September, when the 10-year Treasury was yielding around 5.3%, Insigneo recommended adding duration to portfolios. Although Riesgo pointed out that bond yields are competitive against equities—standing around 5% in both cases, with lower volatility in government debt—he ruled out exiting equities: “You can’t be out,” Cohen agreed, given a cycle underpinned by corporate margin expansion.
Toward the end of the discussion, Riesgo suggested that the relationship between the United States and Latin America could gain strategic weight in the coming years. In his analysis, reduced Washington involvement in the Middle East would open room for greater focus on the hemisphere, citing signs such as U.S. investments in rare earths in Brazil and Treasury Department backing for Argentina. For the executive, this dynamic transcends the Donald Trump administration and reflects a broader shift in America’s international posture: “Absolute power has never been greater, but its relative weight has indeed declined,” he maintained.
Regarding relations with China, Riesgo compared the situation to a new Cold War characterized by cycles of détente and tension, but without a full rupture. “Both sides need each other far more than they realize. They want an economic divorce, but they have too many children and too much shared property together,” he illustrated.
The projected annual return for a U.S. dollar-denominated 60/40 stock and bond portfolio over the next 10–15 years rises to 7.0%, although higher correlations between stocks and bonds call for additional diversification. This is the main takeaway from the 31st edition of the 2027 Long-Term Capital Market Assumptions (LTCMA) report by J.P. Morgan Asset Management. The study offers a comprehensive 10- to 15-year outlook on the future returns and risks across various investment asset classes, against a backdrop where inflation uncertainty and market volatility remain elevated.
While labor and demographic headwinds may constrain long-term growth potential, the report argues that increased capital expenditure and the adoption of artificial intelligence across sectors will bolster near-term earnings and lift long-term productivity.
The report emphasizes the potential of regional equity diversification and the inclusion of alternative assets, particularly hedge funds and real assets. A 60/40+ portfolio with a 30% allocation to diversified alternatives could boost expected returns up to 7.5% and improve the Sharpe ratio by 21% compared to a conventional 60/40 portfolio.
“Our long-term capital market assumptions help investors navigate markets reshaped by economic nationalism, technological acceleration, and shifting capital flows. This year’s outlook points to stronger long-term growth and new opportunities to build more resilient portfolios through diversification—combining higher global fixed-income yields with alternative and real assets that deliver differentiated return sources and enhanced inflation protection,” noted John Bilton, Global Head of Multi-Asset Strategy at J.P. Morgan Asset Management.
For his part, David Kelly, Chief Global Strategist at J.P. Morgan Asset Management, commented: “The global economy is entering a dynamic investment cycle in which AI adoption and productivity gains reinforce growth prospects. At the same time, demographic challenges, elevated public deficits, and a more complex geopolitical landscape suggest that inflation will remain more volatile across our forecast horizon.”
Regarding the report’s practical utility, Grace Peters, Global Co-Head of Investment Strategy at J.P. Morgan Private Bank, explained: “Each year, the assumptions from our LTCMA report provide the foundation for building client portfolios, and that has never been more critical than it is today. Returns matter, but they are no longer the only factor to consider. In the current environment, achieving an optimal balance between risk and return is essential. High market dispersion creates opportunities for investors who take a disciplined approach to strategic asset allocation, looking beyond what the headlines might suggest.”
Key Takeaways from the Report
The firm explains that three core forces are shaping the future and will drive returns. The first is economic nationalism, which spurs state investment, though risks linked to inflation volatility persist. Second, technology adoption is underpinning the global economy by driving investment and productivity. Meanwhile, a surge in domestic investment is prompting a reallocation of capital and altering the dynamics of public and private flows.
The best growth prospects for the developed world in 15 years: The report notes that a global investment boom focused on artificial intelligence, set to extend through 2040, will lift total factor productivity by 50% to 120 basis points. This boost raises the forecast for U.S. real GDP growth to 2.1% and developed-market nominal growth to 4.2%. In addition, the policy mix of GDP and inflation is the most favorable seen since the pandemic.
Furthermore, upward revisions to U.S. equities, a global bond revival, and a maiden analysis of bitcoin take center stage. According to the study, profit margins exceeding 15% lift the forecast for U.S. large-cap equities by 80 basis points to 7.5%, leading developed market equity expectations to surpass emerging markets for the first time in the report’s history. Meanwhile, rising real yields push global aggregate bond forecasts up from a low of 2.1% in 2021 to 5.3% today—the highest level in two decades. The document also includes an expected return range for bitcoin, although the asset is not included as a portfolio allocation.
Regarding alternative assets, they offer superior returns, enhanced diversification, and strengthened inflation protection. Higher inflation volatility, persistent currency debasement risks, and expanding alpha-generation opportunities reinforce the role of alternative assets as an indispensable portfolio component and return engine. The analysis lifts the outlook for diversified hedge funds by 140 basis points, supported by sustained alpha resilience and a higher interest-rate regime. Concurrently, it maintains a constructive outlook on real assets given their capacity to hedge against heightened inflation volatility.
Return Assumptions by Asset Class
Fixed Income
Intermediate-term U.S. Treasuries are expected to deliver a 4.6% return, supported by expectations of higher policy rates and the reconstitution of term premia, which brightens long-term return prospects.
U.S. investment-grade corporate debt is projected to return 6.1%, while U.S. high-yield debt is forecast at 6.7%, with a fair value spread of 440 basis points, driven by improved credit quality among the index’s constituents.
Equities
U.S. large-cap equities are expected to yield 7.5% (up from 6.7% previously), reflecting persistent technology adoption and productivity gains. Nevertheless, elevated starting valuations and concentration risk remain vital considerations. Globally, equities are projected to return 7.5% (in USD), with non-U.S. markets offering richer diversification potential and benefiting from a U.S. dollar depreciation that proceeds at a more measured pace.
For emerging markets, the report projects equity returns of 7.1% (in USD)—a lower figure than the previous year, as AI tailwinds and capital expenditures (capex) normalize.
Alternative Investments
Alternatives encompass several distinct categories:
Private Equity: Projected return stands at 9.8%, marking a slight moderation. Return potential remains anchored to consistent value creation and operational efficiencies, including AI integration across portfolio companies.
Real Estate: Core U.S. real estate is projected to return 8.1%, while European core real estate is set at 7.1%.
Core Global Infrastructure: Forecast to deliver 7.1% (up from 6.5% last year), mirroring supply chain reconfigurations.
Commodities: Broad-basket commodities return forecasts rise to 4.8%, as access to critical minerals remains constrained and geopolitical risks weigh on the outlook. Gold holds steady at 5.5%.
Timberland: Global timberland assets are expected to generate 6.2%, slightly below the 6.3% recorded the previous year.
Hedge Funds: Diversified hedge funds are projected to return 6.7%, up from 5.3% last year, reflecting higher alpha estimates.
The Long-Term Capital Market Assumptions (LTCMA) report is the product of an exhaustive research process combining quantitative and qualitative inputs from more than 90 leading portfolio managers, economists, and research analysts globally. These time-tested projections cover over 200 assets denominated in more than 20 currencies, serving as a benchmark for strategic asset allocation and long-term investment planning across today’s evolving financial landscape.
No changes are expected in the U.S. Federal Reserve’s benchmark interest rate at next week’s meeting. The market takes it for granted that the U.S. monetary authority will choose to leave its monetary policy unchanged, holding rates within the 3.75%–4.00% target range set following last month’s hike. According to asset management experts, the rationale is twofold: the proximity of the midterm elections and the ongoing economic resilience displayed by the United States.
“The proximity of the midterm elections, along with the need to evaluate the impact that the previous rate hike has had on the market, are among the most significant arguments for postponing a decision to raise rates again in October. Consequently, even though the September U.S. inflation print came in worse than expected across both headline and core metrics, it still appears too early to confirm an upward trend. Investors believe Warsh will opt to delay any hike until December, when the market anticipates another increase in the policy rate that will lift the target range to 4.00%–4.25%,” explains Cristina Gavín Moreno, Head of Fixed Income at Ibercaja Gestión.
Between Statements and Data
Furthermore, as Kish Pathak, fixed-income research analyst at MFS IM, and Erik Weisman, chief economist and portfolio manager at MFS IM, recall, comments from Vice Chairs Williams and Jefferson revealed no intention to raise rates this month. Christopher Waller stated that hikes “do not necessarily have to happen at consecutive meetings,” and Bowman sees no urgency to act. Finally, Warsh’s remarks in Bangkok were notable for what went unsaid: he did not repeat the forceful anti-inflation message delivered at Jackson Hole.
“Data published since the last meeting supports the view that the labor market remains in good shape and that inflation is still too elevated for comfort. At the same time, Warsh has favored focusing on broader trends. A single additional month of data does little to determine whether the trend is shifting, which is why he has advocated for reducing the number of FOMC meetings. The nature of the risks confronting the economy also counsels patience. For instance, latent inflationary pressures will ease if some resolution to the war involving Iran is reached and energy prices retreat. The economy has proven resilient amid the oil crisis thanks to robust capital expenditure linked to artificial intelligence and the wealth effect generated by equities. If the recent volatility in AI-related stocks worsens, growth could lose momentum. By December, there will be more visibility on both fronts,” argue the MFS IM experts.
Bank of America (BofA) economists take a more critical view of the headline U.S. economic data, acknowledging that while there are “strong arguments for raising rates, there are substantial hurdles to executing it.” They maintain their forecast that the Fed will raise interest rates by 25 basis points, although they recognize it will be a difficult decision to implement given market developments over the past week. “September inflation, coming in well above expectations, bolsters the case for an October hike. The October decision will test Fed Chair Kevin Warsh’s resolve to introduce a radical shift in the institution’s forward guidance. If the Fed raises rates, fears of excessive monetary tightening could emerge; if it holds rates unchanged, markets might question its credibility,” they state.
A New Way of Communicating
Thus, according to market experts, the primary focus of next week’s meeting lies in the Fed Chair’s assessment of the condition of the U.S. economy. “Even if he does not deliver formal forward guidance, he can certainly offer clues about what to expect—not so much for the remainder of this year, where the market already prices in a December hike, but looking ahead to 2027. If consumer strength persists and inflationary pressures become entrenched, that could lead to two additional hikes next year,” Gavín notes.
According to Christian Scherrmann, Chief U.S. Economist at DWS, in one of his rare public appearances outside the post-FOMC press conference, the Fed Chair refrained from commenting on the monetary policy outlook. “This was widely interpreted as a signal that the Fed will maintain the status quo, likely referencing his Jackson Hole remarks prior to the last rate increase. However, other Fed officials continue to send mixed signals. For example, Governor Christopher Waller still entertains the possibility of further hikes, even as higher Treasury yields tighten financial conditions. Vice Chair Philip Jefferson advocates for patience, while Governor Michelle Bowman sees little urgency to act. Others, such as Austan Goolsbee, Beth Hammack, John Williams, and Susan Collins, worry that inflation could prove stickier than expected. This divergence of views suggests the committee itself is divided over whether policy is already restrictive enough. In any case, central bankers have become more active in recent months rather than less, contrary to what Chair Warsh suggested. We interpret this as a sign of an engaged FOMC, which in our view reinforces the institution’s independence,” Scherrmann emphasizes.
For François Rimeu, Senior Strategist at Crédit Mutuel AM, although he agrees with fellow analysts that forward guidance has fallen out of favor, close attention must be paid to Warsh’s remarks during the ensuing press conference. “The official statement is likely to remain largely unchanged from September: solid growth, a stable labor market without wage pressures, elevated inflation, and a reaffirmed commitment to price stability. In the press conference, Chair Warsh is expected to maintain his stance of avoiding guidance on the future path of interest rates,” he adds.
Funds Society is returning to Chile to convene the local asset and wealth management industries to share conversations and insights, this time in a new format: the Funds Society Leaders Summit, organized in partnership with CFA Society Chile. This gathering is tailored for leaders in asset and wealth management, created by the industry and for the industry.
The event is scheduled for November 17 of this year, starting at 8:00 AM, at The Ritz-Carlton Santiago hotel, located in the Las Condes district. Those who wish to participate must register, as spaces are limited.
With this summit—an event created by the industry, for the industry—the Leaders Summit aims to bring together leaders from asset and wealth management for a day centered on the topics that matter most to and most concern sector professionals.
The agenda, designed in collaboration with CFA Society Chile, will feature top-tier speakers and experts from key areas such as asset management, private banking, family offices, pension funds, and insurance firms, who will discuss the major challenges and trends of the moment.
The program combines dynamic panels with networking sessions, concluding with a cocktail reception to exchange views and continue connecting.
This initiative is made possible thanks to our partner, CFA Society Chile, and our sponsors: Ninety One, Lumyna, VanEck, HSBC Asset Management, Insigneo, and State Street Investment Management.
Funds Society Leaders Summit Chile brings to South America the event format previously held in Madrid and Miami.
Citi Wealth’s recent “2026 Global Family Office Report,” based on responses from 351 family office executives across 41 countries, reveals that leading organizations are constructing long-term strategies grounded in three pillars: capital, capability, and continuity. In an environment characterized by high interest rates, doubts regarding financial system stability, and geopolitical risks, family offices have operated in an agile and disciplined manner. Sector leaders have not allowed uncertainty to paralyze them; instead, they have adopted more deliberate and institutional approaches to investing, deploying technology, and preparing the next generation to preserve wealth.
Extraordinary Performance Amid Uncertainty
Capital management has proven to be exceptionally resilient. Nearly nine out of ten family offices (89%) reported positive portfolio returns so far in 2026. Nearly 60% of respondents reported gains of up to 10%, while 13% reported appreciation in their investments exceeding 15%. The Asia-Pacific region stood out, with 26% of family offices achieving gains above 15%.
Annual return targets reflect a focus on sustainable growth. First, 41% of family offices target returns of 7% to 10%. Another 20% aim for returns between 5% and 7%, while 18% seek margins of 10% to 13%. Finally, in Asia-Pacific, 22% of respondents target annual returns above 15%.
Inflation and Asset Restructuring
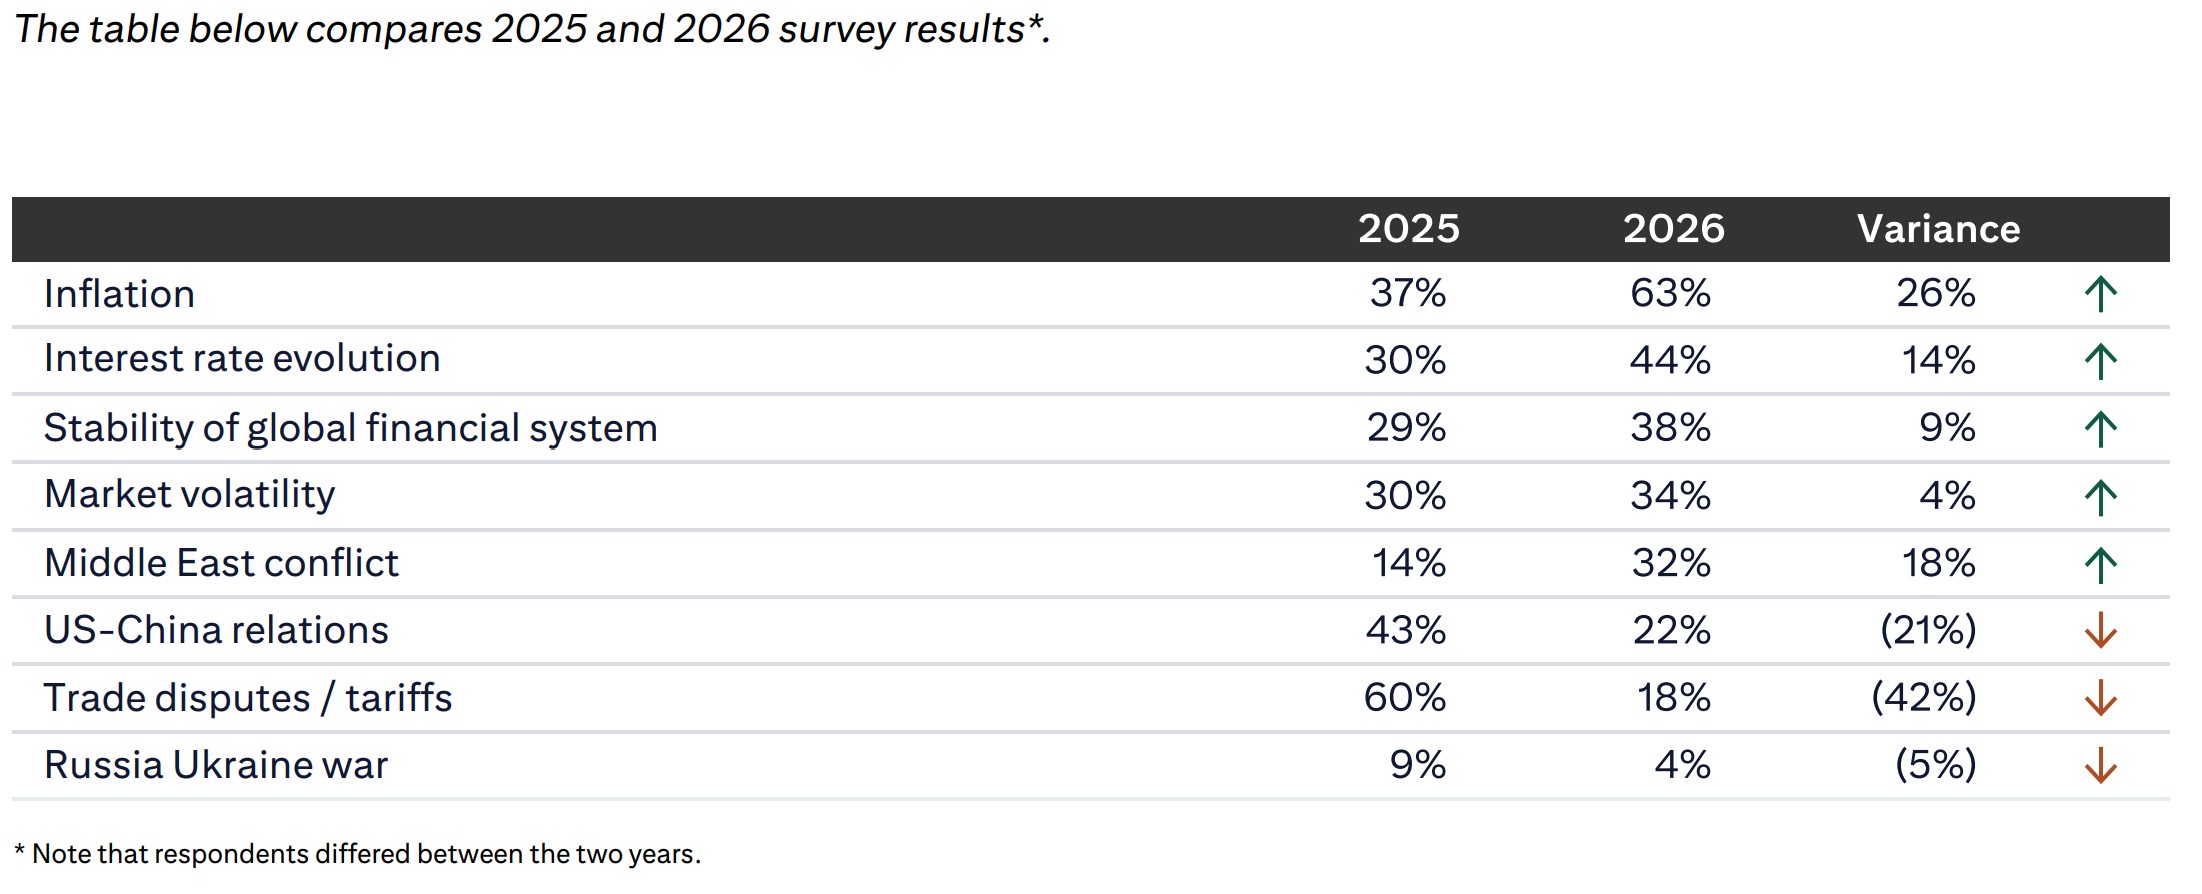
The hierarchy of macroeconomic risks shifted substantially in 2026. Inflation emerged as the dominant concern, cited by 63% of respondents (a significant jump from 37% in 2025). This was followed by interest rate trends (44%) and global financial system stability (38%). Notably, concern over trade disputes and tariffs dropped dramatically to 18%. In Latin America, inflation concerns reached their highest level at 76%.
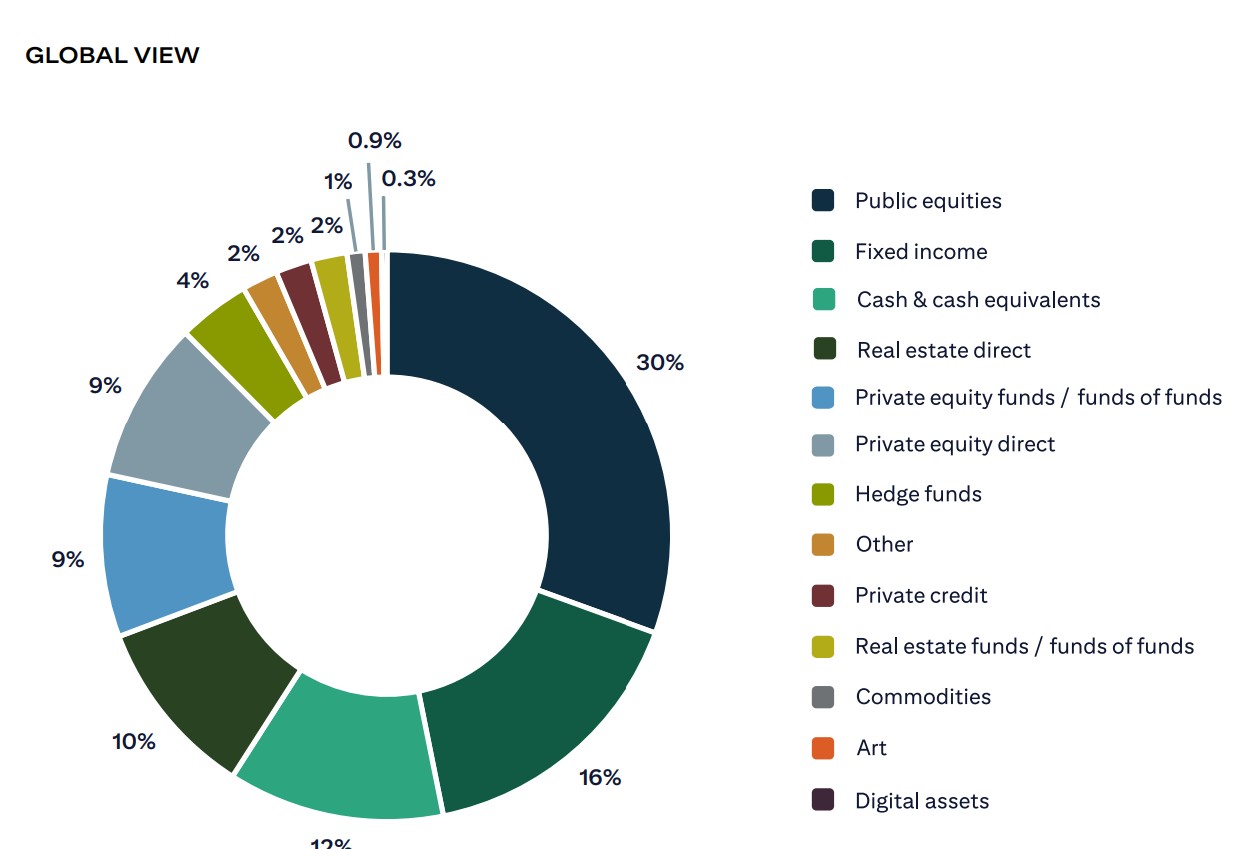
To protect purchasing power, family offices have adjusted their strategic asset allocations. Publicly traded equities currently represent the largest average allocation at 30% of portfolios, followed by fixed income (16%) and cash (12%). Over the past 12 months, equities attracted the largest net capital increase, with 46% of respondents indicating they increased their exposure.
Private Markets and Direct Investment
Private markets remain a fundamental pillar. Looking at private equity, interest is heavily concentrated in growth equity strategies, where 30% plan to increase their allocation. This is followed by venture capital (21%) and secondary transactions (19%).
Direct investment is a widespread practice, with 75% of family offices participating. Growth stage (Series C or D) is the most frequent target area (57%), followed by pre-IPO opportunities in second place (40%), and secondary transactions capturing 40% of respondents.
At the sector level, artificial intelligence (AI) has established itself as the top destination for direct investments, selected by 51% of participants. Healthcare (32%) and real estate (31%) also maintain solid demand. The preferred deal size for these investments ranges between $1 million and $5 million for 44% of family offices, although 26% of the largest firms (with wealth exceeding $500 million) target check sizes between $5 million and $10 million.
Adoption of Artificial Intelligence
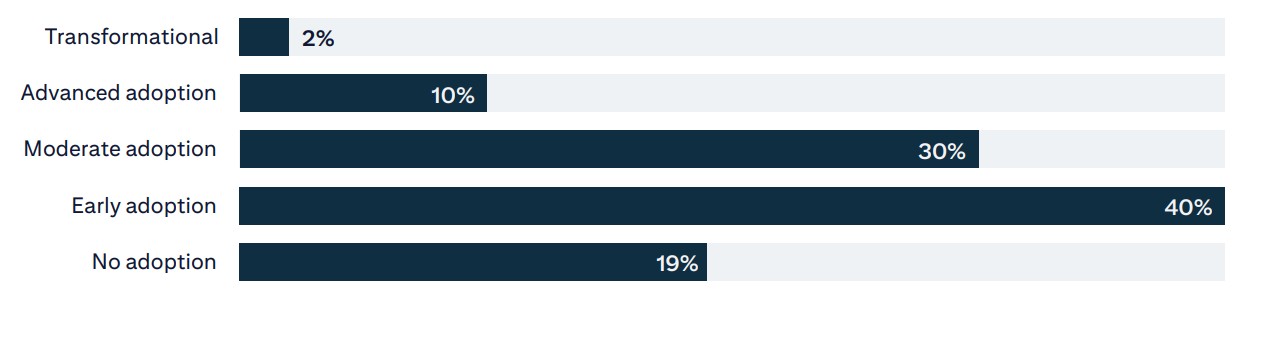
Artificial intelligence has transitioned from an exploratory concept into an operational reality. Forty percent of respondents describe their adoption of AI as early-stage, while an additional 30% report moderate adoption. Only 10% report advanced usage. Just 19% indicate no adoption at all—a significant improvement compared to last year.
Primary applications focus on productivity: generating meeting notes and summaries (16% extensive use and 22% in implementation) is the leading use case. In terms of tangible benefits, 67% state that AI has dramatically improved the speed of information processing. Other positive impacts include reducing manual work or headcount (35%) and faster due diligence (35%). In investment management, market and macroeconomic analysis leads adoption, with 12% using it extensively.
Financing and Operating Companies
The link to operating businesses remains strong: 67% of respondents hold controlling stakes in one or more operating businesses. In terms of banking services for these businesses, 40% require capital or credit lines. As for the family offices themselves, 57% turn to securities-based lending or margin facilities as their primary form of leverage, favoring capital efficiency without disrupting their portfolios.
Continuity, Governance, and Succession
Leadership succession is emerging as one of the most pressing issues on the horizon. One-third of family offices expect a leadership transition within the next five years. However, readiness remains deficient: only 17% feel “well prepared,” while 34% consider themselves “somewhat prepared.”
Among the main challenges, the primary obstacle is the lack of a clear leadership succession plan (29%), followed by insufficient preparation of future leaders (24%), and a lack of a clear vision and goals for the future (22%).
When developing the next generation, 46% cite “lack of clarity regarding future roles” as their biggest hurdle, followed by an “insufficient sense of urgency” (42%) and “lack of engagement from the next generation” (39%). To address this situation, family offices are betting on participation in family meetings (56%), meetings with advisors (47%), and professional experience outside the family business (44%).
Cross-Border Complexity and Globalization
Family wealth is internationalizing rapidly. Thirty-eight percent of respondents expect family globalization (living abroad, acquiring new residences, or obtaining citizenships) to increase moderately or significantly over the next five years. This trend is especially pronounced in Latin America, where 58% expect a global impact.
Currently, 26% of family offices operate across multiple jurisdictions, and another 14% are considering doing so. The number one need for cross-border wealth management is tax coordination (59%), followed by asset structuring (43%) and residence/citizenship planning (35%).
Family Values and Purpose
Decisions are deeply rooted in principles. Fifty-five percent of respondents state that family mission and values strongly guide or fundamentally shape their investment strategy. This figure rises to nearly 80% among third-generation family offices and beyond. Nearly half of family offices maintain allocations to sustainable investments, with public equities (23%) and private equity (21%) being the preferred vehicles.
To enhance philanthropic impact, respondents prioritize access to networks and learning opportunities (25%) on par with intergenerational engagement and legacy building (25%), balancing external effectiveness with internal cohesion. In the realm of art, 17% would consider working with art advisors to gain intelligence on the global market.
Investors are closely monitoring social unrest in Europe, led mainly by France. According to experts at international asset managers, October could be a complicated month for global markets considering the US midterm elections, rising bond yields, and geopolitical and domestic political risks, which do not appear to be losing momentum.
“October is a month that strikes fear into the heart of many investors due to the dramatic, high-profile sell-offs experienced that month in 1929, 1987, and 2008. The negative perception of October is more psychological than real, as historically it has not been the worst month for stock market investing. However, psychology is important when it comes to the markets, and with bond yields hitting multi-year highs, several major elections around the corner, and the US midterm elections just a month away, it seems October is taking us straight into the danger zone,” acknowledges Kristina Hooper, Chief Market Strategist at Man Group.
From Aberdeen Investments, they note that short-term selling pressure may not be over. “Rising oil and gas prices have highlighted pre-existing weaknesses in the fiscal credibility of the US, the UK, and France, as well as persistent inflation, while forced liquidations by leveraged investors have amplified these moves. The only factor that could clearly halt this trend is an improvement in the geopolitical situation in the Middle East,” they indicate.
The Case of France
For now, the big focus is France, as spreads on its sovereign debt have reached new highs while fiscal consolidation seems increasingly distant. It is worth noting that the wave of riots and violence that has broken out responds to social discontent resulting from government cuts and rising inflation. “With the French 10-year bond close to 5%, the 140-billion-euro net savings program proposed by Le Pen arouses skepticism by requiring a gross adjustment of 185 billion euros and relying on unrealistic GDP growth of 1.8%, compared to real estimates of between 0.5% and 0.8% for 2026. The lack of a solution to the French deficit revives the ghost of the 2012 sovereign debt crisis, placing the European Central Bank before the dilemma of letting debt fall and harming confidence in the euro, or intervening and rewarding fiscal indiscipline, creating moral hazard in the rest of the region,” points out Javier Cabrera, analyst at XTB.
For Erick Muller, Director of Product and Market Strategy and Co-Head of the Asset Allocation Group at Muzinich & Co, political gridlock and the proximity of the 2027 elections make it difficult to adopt corrective measures and could prolong uncertainty in the markets. “France is a good example of the difficulties developed economies face in controlling public spending. In 2026, its deficit stands at around 5.6% of GDP, and the interest cost on debt is increasing considerably. This year, interest expenditure has gone from a forecast of 70 billion euros to approximately 80 billion. In 2027 it could reach 92 billion, and in 2028 be close to 100 billion. To put these figures in perspective, the government is trying to find savings of 53 billion euros, something I don’t think it will achieve. We are talking about an increase of around 30 billion in interest payments in just three years. It is a very difficult situation to solve,” he explains.
In his opinion, France’s problem is that the economy is slowing down and the political landscape makes any fiscal response extremely difficult. “Expected growth for 2026 has been reduced to practically half of what was initially expected, which also affects public accounts. Markets are asking what the answer is to this deterioration, and for now, they are not finding any satisfactory one,” he adds.
Return of the Bond Vigilantes?
In this context, investors are paying close attention to the spike in debt yields and the course of the Federal Reserve—have the “bond vigilantes” returned? For Giordano Lombardo, founder, CEO, and CIO of Plenisfer Investments (Generali Investments), yes; furthermore, he warns that the boom in AI investment, increasingly financed by debt, and rising public deficits are increasing pressure on fixed-income markets and elevating stagflation risks.
According to his analysis, the increase in bond yields extended to public securities of other countries. “All major fixed-income markets registered negative returns, except China. In recent weeks, concerns surrounding government bonds of certain Eurozone countries have resurfaced strongly, and France seems to be the epicenter of the crisis this time due to the sharp increase in its public deficit and the prospect of elections that could further worsen the sustainability of public finances,” he states. Moreover, he considers that waves of pessimism in the fixed-income market also affected the technology sector.
His main conclusion is that we have entered a phase of structural bear market conditions for bonds. “However, in recent months, the role of the Federal Reserve has once again become the dominant factor driving short-term movements in the bond market. In addition, the fiscal policies of major economies have all been expansionary, at least over the last fifteen years and especially following the post-pandemic measures introduced in 2020. In the US and Europe, there do not appear to be political forces interested in returning to the fiscal discipline of previous decades,” he qualifies.
Fabrice Chemouny, director of Chief Client Officer.
Natixis Investment Managers (Natixis IM) has announced the creation of the Global Client Development division, which will bring together all teams involved in client services across the entire value chain. According to the asset manager, the new division will feature three areas: Client Markets, organized into six geographic regions; Partnerships; and Product Range & Solutions.
Additionally, it announces that Fabrice Chemouny, current Head of International Distribution, will lead this division as Chief Client Officer. He will assume his new role on January 1, 2027, reporting directly to Philippe Setbon, CEO of Natixis IM. As clarified, this new organizational structure will be implemented following the conclusion of the information and consultation process with the relevant employee representative bodies.
This new organization is part of Groupe BPCE’s VISION 2030 strategic plan. Based on Natixis IM’s ambition for organic growth, this transformation aims, in particular, to adapt the firm’s distribution model to accelerate its global growth and better respond to client needs.
According to the announcement, the creation of a single global platform, which will integrate the United States and other international markets, will foster synergies across regions, provide clients with access to the full range of investment capabilities of Natixis IM and its affiliated investment managers, and enhance operational agility.
The new division will be structured around three main pillars. First, Client Markets, which is a single distribution platform organized into six regions, with each region focused on meeting the needs and investment preferences of its clients, taking into account local market regulations and specifics: United States; Northern Europe and Canada: United Kingdom, Netherlands, Nordics, and Canada; Continental Europe and Latin America: Western and Southern Europe, including France; Central and Eastern Europe; Latin America; and US Offshore; Middle East, Central Asia, and Africa; Asia-Pacific, excluding Japan; and Japan.
Second, a new Partnerships area, whose mission will be to strengthen existing strategic distribution alliances and establish new ones with banking networks, insurers, and other distributors worldwide, with the goal of making Natixis IM’s offering accessible to a broader client base. And finally, a new Product Range & Solutions department. As explained, this area will define the product range strategy based on client needs, developing solutions in areas such as retirement, long-term savings, and wealth management, drawing upon the offerings of investment managers affiliated with Natixis IM.
“We are a global player with deep local roots. In an increasingly fragmented international environment, we want to strengthen both dimensions. Our strategic plan has proven successful, and we want to take it a step further. This new organization further reinforces the central role of clients in our model across all regions and helps accelerate our growth,” stated Philippe Setbon, CEO of Natixis Investment Managers.
For his part, Fabrice Chemouny, who will assume the role of Chief Client Officer of Natixis Investment Managers effective January 1, 2027, added: “By bringing our teams together into a new global organization, we combine a deep understanding of each market with the strength of an international player. Furthermore, we will make our offering accessible to a greater number of clients through new distribution alliances and work with them to develop solutions tailored to their long-term needs. This transformation will provide us with the agility needed to navigate volatile markets, foster synergies across regions, and drive innovation for the benefit of our clients.”
From a former avenue of mansions in Miami to rural land transformed into corporate centers in Texas, these districts concentrate banks, wealth managers, and investment firms that manage billions of dollars. The Wall Street of Latin American offshore is not a single street: it is a network of districts where regional wealth finds infrastructure, specialists, and connections to global markets.
On the Latin American financial map, there are streets that function as more than just corporate addresses. They are meeting points for high-net-worth individuals, international banks, investment managers, tax advisors, lawyers, and firms specializing in preserving and transferring wealth.
From their offices, investment strategies are designed, wealth structures are organized, and the financial needs of entrepreneurs, families, and major investors in the region are served.
Brickell Avenue, in Miami, is probably the most representative example of this geography of money, but it is not the only one. In Houston, Post Oak Boulevard brings together private banking offices and wealth managers; in Dallas, the Crescent Court complex houses major wealth management firms. They are enclaves with distinct characteristics, but they illustrate how US financial infrastructure allows serving capital that crosses borders.
Calling them the Wall Street of Latin American offshore is useful to understand their importance by comparing them to that iconic New York street, although in reality they are not stock exchanges in a strict sense, nor does all the wealth they manage belong to Latin Americans. Their relevance lies in the concentration of institutions, specialists, and services that allow managing international fortunes from the United States.
Brickell Avenue: The Heart of the Latin American Business
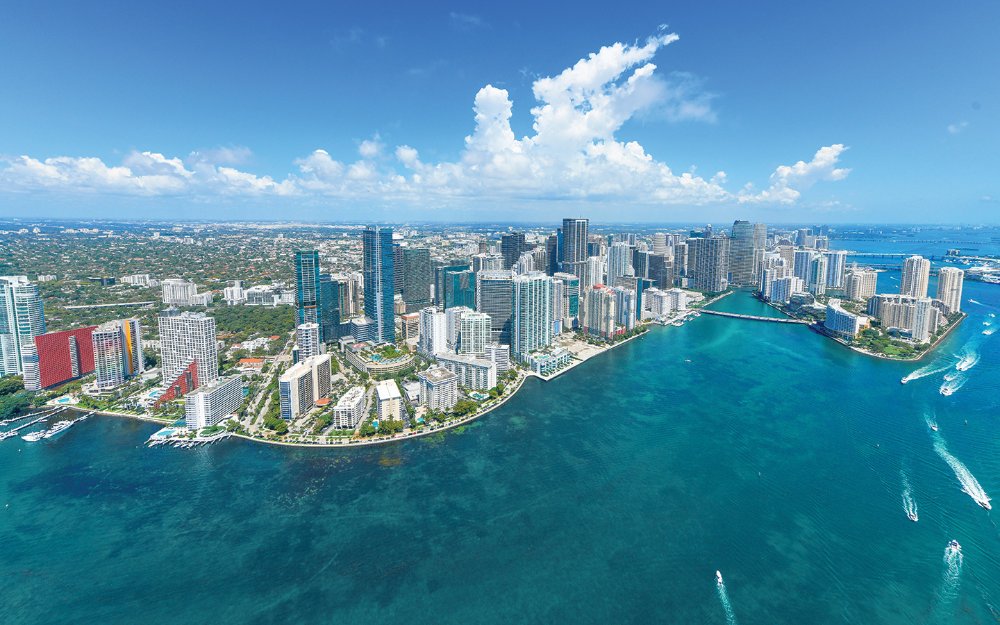
If there is an address that allows visualizing the connection between Latin American wealth and the US financial system, it is Brickell Avenue. The Brickell district, in downtown Miami, combines corporate buildings, bank offices, and firms specializing in investments, with an advantage that another US financial center can hardly replicate: its historical relationship with Latin America.
But what was or what existed before on that street? In the early 20th century, Brickell Avenue had little to do with the skyscraper landscape that today identifies Miami’s financial district. It was a residential area, with large houses and mansions built by some of the most prominent families of the young city. Its prestige was such that the corridor came to be known as Millionaire’s Row, the avenue of the millionaires.
The presence of international institutions is not merely symbolic. J.P. Morgan Private Bank, for example, maintains offices at 1450 Brickell Avenue, where it offers private banking, investment, and wealth advisory services. Morgan Stanley, for its part, announced in 2016 the opening of an office at 1111 on the same avenue, specifically dedicated to wealth management for clients residing in Latin America.
The presence of these players responds to a business logic: major wealth requires more than just managing a portfolio of stocks and bonds. They demand access to global markets, credit, estate planning, fiduciary structures, geographic diversification, and coordination of tax and corporate matters with specialists in different jurisdictions.
In that ecosystem, Brickell’s offices function as access points to much larger financial platforms. A client’s wealth can be distributed among different asset classes, custodians, and jurisdictions, while the relationship with the banker and much of the advisory services are concentrated in Miami.
The importance of the city also transcends a single avenue. Downtown Miami and Brickell are part of an office market in which international financial firms compete for strategic locations. According to Colliers, in the fourth quarter of 2025, the Brickell, Downtown Miami, and Coral Gables submarkets each recorded more than 400,000 square feet of Class A office leasing during the year. The data does not correspond exclusively to financial institutions, but it confirms the scale of the corporate market in which they operate. (Colliers, Miami-Dade Office Market Report, January 2026).
Brickell, furthermore, does not exhaust the business map. Coral Gables and other areas of Miami-Dade host bank offices, wealth managers, and professional service providers. For this reason, rather than reducing the industry to a single street, it is convenient to understand it as a financial corridor whose most recognizable core is Brickell.
Houston: Post Oak Boulevard and the Management of Major Fortunes
Texas offers another piece of this geography, although with a different specialization. Houston combines an economy historically linked to energy with an extensive private banking, financial advisory, and wealth management industry. That structure is relevant for entrepreneurs, investors, and families with interests in Mexico and other Latin American markets, especially when their businesses are linked to energy, infrastructure, and cross-border trade.
One of the most visible points is Post Oak Boulevard, in the Uptown and Galleria area. Offices of institutions offering investment, private banking, and wealth management services are located there.
The history of Post Oak Boulevard shows an even more radical urban transformation. In the 1940s and 1950s, the Uptown area, west of downtown Houston, was surrounded by open land, agricultural areas, and new residential developments. Post Oak was then a two-lane road that ran through prairies and fields, flanked by drainage ditches.
The turn began with post-war commercial development. In 1951, the Sakowitz department store bet on the area; later, other establishments and commercial projects arrived. The decisive moment was the opening of The Galleria, in 1970, promoted by developer Gerald Hines on land that still retained part of its rural character.
Today, an indicator of the dimension of the business appears in Morgan Stanley Wealth Management. The firm reported that its Houston Post Oak market, made up of three offices, had 145 financial advisors, 75 support employees, and four private bankers, in addition to a management and specialized team. Together, that operation supervised $56 billion in client assets and generated annual revenue of $355 million, according to data reported as of October 15, 2025.
The figure requires a precision: it corresponds to Morgan Stanley’s Houston Post Oak market, not to all assets managed by institutions located on the avenue, nor exclusively to Latin American clients. However, it offers a concrete measure of the scale that a wealth advisory platform can reach in this district. (Morgan Stanley Wealth Management, Houston Market Institutional Information).
The corridor also brings together other participants. Texas Capital Private Bank has offices at 1330 Post Oak Boulevard, where it offers wealth advisory, investment management, credit solutions, fiduciary services, and private banking. BBVA, for its part, announced in September 2025 the opening of an office at 1980 on the same avenue to strengthen its corporate and investment banking activities in the United States, expand Global Wealth Advisory services, and reinforce its service to Mexican clients.
BBVA’s presence is particularly significant due to the financial relationship between Mexico and Texas. The entity presented the new office as part of its US expansion strategy, with specialized capabilities in energy and clean technologies, in addition to corporate and wealth services. (BBVA, September 2025).
Post Oak Boulevard represents, therefore, a node in which business wealth, banking services, and wealth management converge. Its link with Latin America is different from Miami’s: less focused on the historical specialization of an international hub for regional fortunes and more connected to the economic activity, business, and financial needs that link Texas with Mexico and other markets.
Dallas: Crescent Court and the Business of Preserving Wealth
In Dallas, the wealth map has one of its most recognizable points at Crescent Court, in the Uptown area. The complex houses offices of major institutions offering investment management and services for high-net-worth families and individuals.
In the early 1980s, several plots of land north of downtown Dallas were occupied by former car dealerships. Developer Caroline Hunt and Rosewood Corporation acquired those properties to build a mixed-use complex that would contribute to transforming the Uptown area.
The project, known as The Crescent, opened in 1986. Its estimated investment was $400 million, an extraordinary figure for a real estate development at that time. The complex incorporated three office towers, a hotel, and retail spaces, in addition to a five-level underground parking garage with capacity for approximately 4,100 vehicles.
Currently, UBS maintains a wealth management office at 100 Crescent Court, while J.P. Morgan Wealth Management has a presence in the same complex. Both institutions offer services ranging from investment advisory to financial planning and strategies to preserve and transfer wealth.
Dallas’s importance does not depend solely on the international entities located in this complex. The city is part of a Texas economy with major companies, business owners, and families with accumulated wealth in sectors such as energy, real estate, technology, and services. That base fuels the demand for wealth management, estate planning, credit, and investment diversification.
For Latin American capital, Dallas constitutes an alternative within the US network of financial services, although it should not be automatically equated with Miami as a specialized center for international Latin American clients. The existence of offices of major banks confirms the depth of its wealth market, but it does not allow attributing a specific volume of Latin American assets to them without additional data.
A Network of Institutions, Not a Single Street
The addresses above show that the Latin American offshore business in the United States is not concentrated in a single building or a single city. It operates through a network of offices, banking platforms, and specialized providers whose function is to connect clients with global financial markets, products, and services.
Miami stands out for its international specialization and its links with Latin America. Houston combines wealth management with a business base closely related to energy and trade. Dallas, for its part, offers an extensive private banking and wealth advisory infrastructure for major fortunes.
The difference matters because the term offshore does not necessarily describe an opaque structure or an operation intended to evade tax obligations. In this context, it generally refers to the management of assets outside the owner’s country of residence. It is an activity that can include international investments, custody, estate planning, and global banking services, always within applicable legal frameworks.
For this reason, the power of these districts is not measured solely by the number of banks that have their offices on the same avenue. It also resides in the ability to bring together in a relatively small space those who design strategies, manage relationships with clients, connect investments with global markets, and coordinate legal, tax, and fiduciary services.
For Latin American families seeking to diversify their assets outside their countries of origin, these hubs offer access to a financial infrastructure that is difficult to replicate in a single place. For institutions, they represent markets in which proximity to the client, specialization, and the ability to coordinate multiple services can become competitive advantages.
The image of a Latin American Wall Street distributed among Brickell, Post Oak, and Crescent Court helps to understand this reality, provided it is recognized that these are centers with different functions and that the money managed by each firm does not necessarily equal Latin American wealth.
Ultimately, the power of these streets lies in their ability to connect the wealth of Latin America with the international financial system. Behind the facades of their buildings, there are not just offices: there are investment, advisory, and wealth management platforms that form part of the infrastructure with which the region’s major capital moves beyond its borders.
The specialized consulting firm ETFGI has announced that the US ETF industry has broken its annual net inflow record by reaching $1.56 trillion raised in September. This figure brings assets invested in exchange-traded funds in the country to $16.24 trillion at the end of that month.
During September, the US ETF industry recorded net inflows of $152.93 billion, bringing the year-to-date total to $1.56 trillion, according to the September 2026 monthly report prepared by the firm.
According to the study, assets increased by 21% year-to-date, growing from $13.44 trillion at the end of 2025 to $16.24 trillion. This marks the 53rd consecutive month of net capital inflows, putting the year-to-date figure at $1.56 trillion, compared to the $1.50 trillion recorded in 2025.
The annual growth of cumulative net inflows continues to rise each year, going from $740.78 billion in 2024 to $951.27 billion in 2025, reaching $1.56 trillion in 2026.
Additionally, the supply of ETFs has expanded this year, with 206 providers launching 1,130 new exchange-traded funds, compared to 238 that have closed in 2026.