Morgan Stanley’s Endorsement of Equities: Valuations Are Grounded in Fundamentals

  |   By  |  0 Comentarios

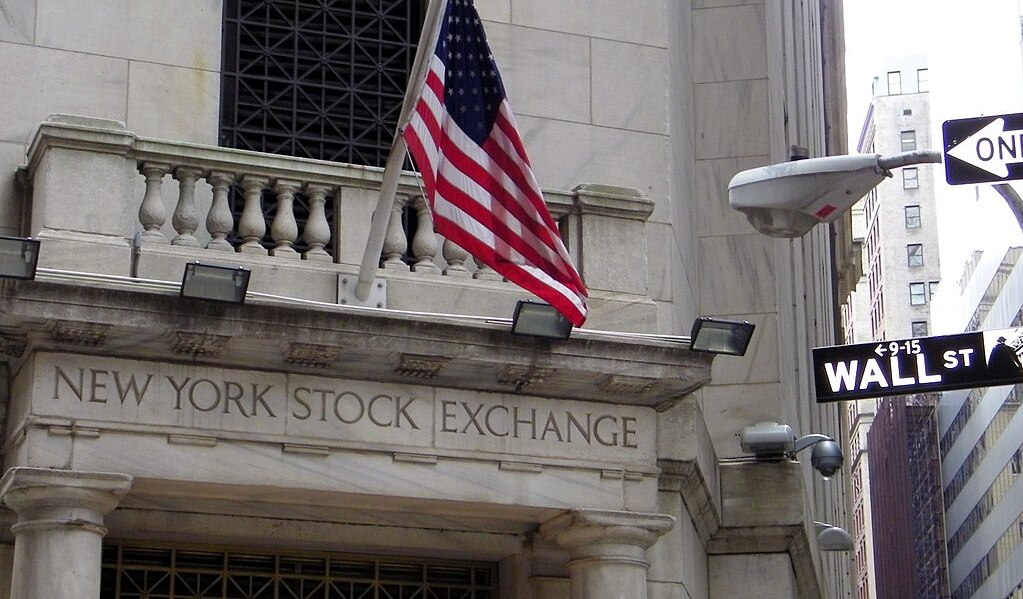
Wikimedia Commons

In its latest positioning report, the investment bank described valuations as “reasonable,” given corporate earnings prospects and nominal GDP growth.

According to the firm, corporate earnings remain the primary driver of the equity rally, a variable they expect to continue trending upward.

Morgan Stanley holds a particularly bullish view on the U.S., which is the only equity market they currently recommend overweighting.

Despite a global economic environment marked by inflation, uncertainty, and geopolitical tension, global equity markets have been on a run. With varying results across geographies and sectors, global equity benchmarks have risen strongly, driven primarily by the excitement surrounding the artificial intelligence boom, which has had Wall Street, in particular, as one of its epicenters. And while this positive momentum has raised several questions—and anxieties—around equity valuation levels, prices are supported by fundamentals. That is Morgan Stanley’s stance on the matter.

According to the bank’s latest global positioning report, BEAT (an acronym for Bonds, Equities, Alternatives, and Transition) for the third quarter of the year, economic fundamentals support valuations.

“While headline valuations appear elevated, they remain reasonable relative to earnings growth prospects and a structurally stronger nominal economy,” the investment bank noted in its recent report.

Along those lines, they added that they expect “the market to broaden out as geopolitical tensions ease, with many sectors still trading at lower valuations, leaving room for a rebound.”

Regarding the recent upside in equity markets, Morgan Stanley emphasized that it has been driven by corporate results rather than higher multiples. Current multiples, they noted, “are not extreme when viewed relative to the last five to ten years.”

Tailwinds for Stock Markets

One of the drivers Morgan Stanley sees for equities is related to economic dynamics. “Stronger nominal GDP growth supports corporate revenue expansion, earnings growth, and cash flow generation, creating a favorable environment for equities,” they commented in their report.

Added to this is the public policy component, given that the investment bank anticipates that fiscal policies, deregulation, and tax-driven growth “are likely to reinforce this.”

For the firm, corporate earnings remain the primary driver of the equity rally. Looking ahead, they anticipate this variable will continue to trend upward, supported by “resilient demand, productivity gains, and expanding capex cycles.” This trajectory, they predicted, will run its course as long as the capital expenditure cycle continues to rise.

Currently, an expanding capex cycle is closely tied to the rapid adoption of artificial intelligence models across all levels of the economy, in what many describe as a new industrial revolution. This deployment of corporate muscle has helped keep investor optimism alive amid uncertainties.

An Interesting Dynamic in the U.S.

Stock markets overall have posted relatively solid performance. The MSCI All Country World Index, which tracks global equities broadly, has gained 18.2% over the last 12 months. The United States as a whole has performed on par with the rest of the world—with one-year gains of 16.6% for the MSCI USA Index and 16.7% for the MSCI World ex USA Index—but its technology sector has stood out in particular.

Reflecting this, while the S&P 500 has appreciated 16.7% over 12 months and the Dow Jones Industrial Average 11.8%, the Nasdaq Composite has surged 20.4%.

Echoing its positive view on the fundamentals behind equity valuations, Morgan Stanley sees room for Wall Street to run further. In fact, in its positioning recommendations, the U.S. stock market is the only one rated Overweight.

This recommendation is backed by a “constructively positive view on overall growth and earnings in 2026.” In that regard, they highlighted that fiscal stimulus from the country’s One Big Beautiful Bill, deregulation efforts, and ongoing AI adoption “continue to support growth.”

In contrast, the firm holds a Neutral view on Japanese and Emerging Market equities, and an Underweight recommendation on European equities.
The Shadow of a Strong El Niño Phenomenon Extends Across Latin America

  |   By  |  0 Comentarios

Wikimedia Commons

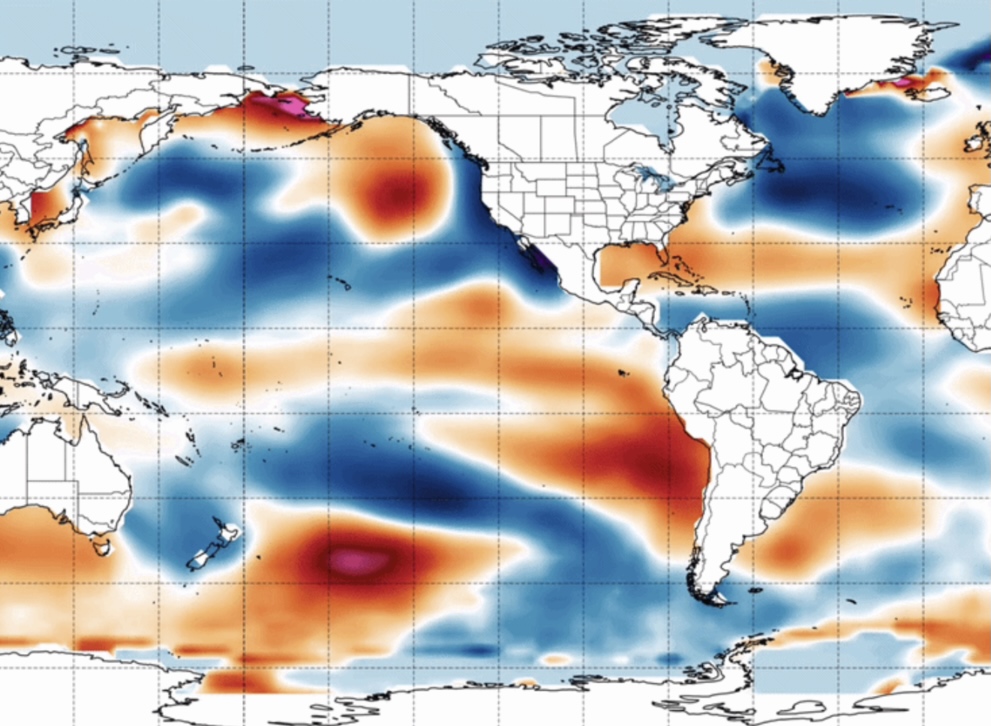
With anxieties over a strong version of the El Niño phenomenon confirmed, markets are preparing to deal with the economic impacts across Latin American countries. The consensus is that there will be widespread consequences due to the disruption of markets such as energy and agriculture, but also areas where opportunities could arise. Furthermore, financial sector actors point out that not all countries in the region experience this climate phenomenon in the same way or with the same intensity.

United Nations analyses warn of an El Niño of historic magnitude. Estimates from the National Oceanic and Atmospheric Administration (NOAA) assign a probability of over 90% that the phenomenon will reach a very high intensity during the northern autumn-winter period (spring-summer in the Southern Hemisphere). What’s more, they place the probability of it reaching a historic level—the so-called Super El Niño—at 69%.

Economic impacts are going to be deeply heterogeneous and persistent, according to comments by the Economic Commission for Latin America and the Caribbean (ECLAC) in a recent report. The entity anticipates a real GDP contraction, inflationary pressures, poverty, and critical vulnerability in key sectors such as energy, fishing, agriculture, and certain infrastructure.

Neuberger shares the view that the ocean warming phenomenon can have “substantial” consequences. Disruptions in agricultural production, food security, and power generation can feed inflation, against a backdrop where consumer prices are already trending upward with the jump in oil and the prolonged conflict in the Middle East.

A Second Phase of the Phenomenon

“It is expected to have an impact in two phases. The first has already been taking place this year,” says Jorge Espada, co-founder and Managing Partner at Valoro Capital. The first relates to the warming of waters and climate, mainly affecting primary activities.

In the case of Peru—one of the countries that tends to be most affected by El Niño—sectors like fishing were hit, impacting anchovy production, among others, as well as certain crops like mango, both for export and domestic consumption.

Now, concern is linked to the second phase of the phenomenon, a period expected to extend between November of this year and March of next year. “We are watching what could be the second phase, which is expected to be the strongest,” Espada explains. This stretch, associated with heavy rains, could damage infrastructure and cause road closures.

This generates larger losses, he adds, “damaging the economy’s payment chain,” though he also notes that both businesses and the government are taking measures to prepare, especially in specific areas.

All in all, the expectation is that the impact will be widespread. ECLAC calculations point to an extreme El Niño generating a cumulative loss of at least 2% of regional GDP over a three-year period, “half of which will be concentrated in the first year following the climate event.” At the same time, they expect the effect on households could increase poverty in Latin America by up to 4.8 million people toward the end of the decade, compared to a scenario without the climate phenomenon.

Main Effects

“Countries in Latin America and Southeast Asia tend to be among the most exposed. Economies like Peru, Ecuador, Colombia, Indonesia, and the Philippines are particularly sensitive given their exposure to agriculture, fishing, and weather-dependent energy infrastructure,” Neuberger notes. Ecuador, for example, gets 78% of its energy from hydroelectric sources, meaning a severe drought could affect energy supply, driving up prices and impacting growth.

On the other hand, some countries could even benefit, as rainfall patterns could support agriculture and power generation. “Argentina, for example, where agriculture represents around 50% of exported goods, benefits from heavier rains in its agricultural heartland of the Pampas,” the asset manager indicated in a recent market commentary. Paraguay could also benefit on the energy side.

The financial sector could also be affected by El Niño, although “it is still too early to gauge the impact,” as highlighted by JPMorgan. Banco do Brasil, for instance, is seen as the most exposed firm, given that agribusiness is linked to a third of its credit portfolio. However, since clear performance trends in soybeans and corn have not emerged in previous cycles, “it is too early to determine a direction.” For now, they anticipate the company will continue to be impacted.

Among insurers, they identified India’s IRB and Brazil’s BB Seguridade Participações as the most exposed to the climate risk associated with the phenomenon, followed by Porto Seguro, also Brazilian. “We recall that agricultural business insurance primarily protects against production losses, rather than price fluctuations,” they emphasized in a recent report.

Leopoldo Ferris Wallis Joins Insigneo’s Network of Investment Professionals

  |   By  |  0 Comentarios

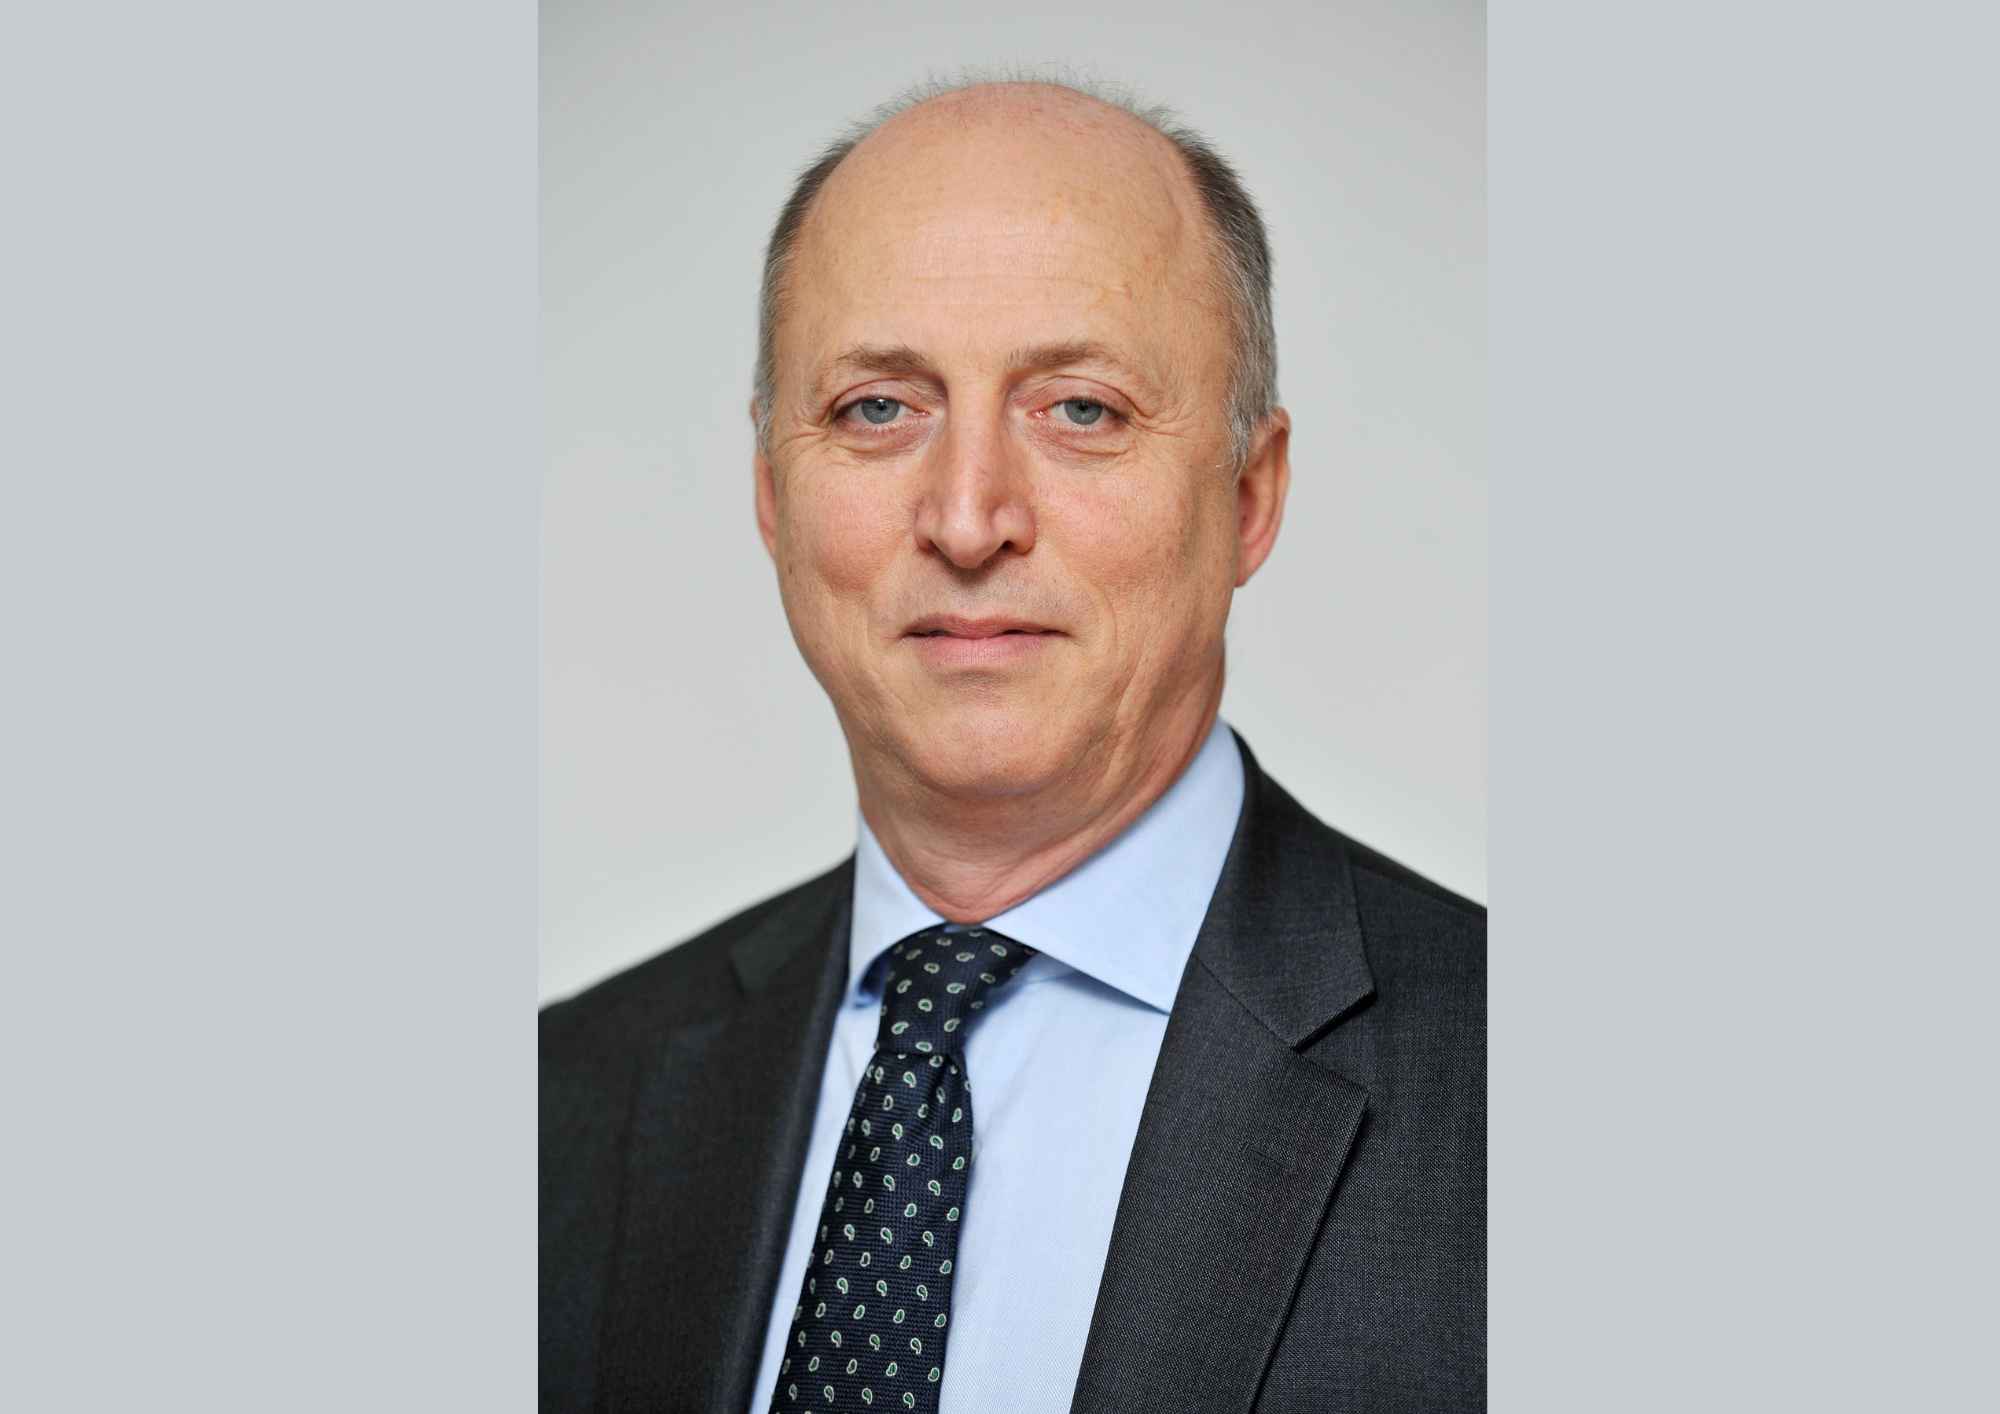
Photo courtesyLeopoldo Ferris Wallis, Investment Professional at Insigneo

Insigneo, a leading international wealth management firm, is pleased to welcome Leopoldo “Leo” Ferris Wallis as an Investment Professional. Based in New York, Ferris joins Insigneo’s network of professionals, bringing more than three decades of experience in international wealth management, private banking, and offshore business development. Ferris will conduct his wealth management business through REL Capital, an entity registered as a d/b/a within Insigneo’s network, reflecting both his established practice and Insigneo’s model of supporting advisor-led businesses through its comprehensive wealth management platform.

“Joining Insigneo represents an exciting step in my career and an opportunity to continue growing REL Capital through a platform with robust international capabilities,” said Leopoldo Ferris Wallis, Investment Professional at Insigneo. “I look forward to continuing to serve clients with a tailored approach, while leveraging the resources and solutions available across the Insigneo network.”

Prior to joining Insigneo, Ferris served as Senior Vice President at Oppenheimer & Co. in New York, where he managed client portfolios and developed long-term relationships with institutional and high-net-worth private clients. His career also includes senior positions at Morgan Stanley, Banco Santander International, Banco Español de Crédito, Banco Provincial (BBVA), and Banvenez Trading. Throughout his career, he has focused on complex portfolios, strategic market development, and tailored solutions for high-net-worth individuals and institutional clients. Ferris holds a Bachelor of Arts degree from Indiana University Bloomington and an MBA from Boston University. He also completed the Advanced Management Program at IESA in Caracas, Venezuela.

“We are delighted to welcome Leo to Insigneo and to our growing New York team,” noted Alfredo J. Maldonado, Market Head for New York and the U.S. Northeast at Insigneo. “His extensive background in international wealth management, private banking, and cross-border markets will be a valuable addition to our network, and we look forward to supporting him as he continues to build his business and serve his clients.” The addition of Ferris further strengthens Insigneo’s presence in New York and underscores the firm’s ongoing focus on attracting experienced investment professionals seeking a platform built to support independent, client-centric business models.

Ted Stratigos (Aladdin Wealth Tech): “Institutions Demand Technology Capable of Connecting Investment Ideas, Model Portfolios, Execution, and Oversight”

  |   By  |  0 Comentarios

Photo courtesyTed Stratigos, Global Head of Aladdin Wealth Tech.

As wealth management continues to evolve, institutions are seeking ways to combine the personalization and trust of traditional private banking with the scale, efficiency, and analytical capabilities demanded by today’s clients. In the experience of Ted Stratigos, Global Head of Aladdin Wealth Tech, this requires technology that empowers advisors through a comprehensive view of client needs, deeper portfolio analysis, and the ability to deliver consistent, tailored advice with greater confidence and efficiency. We discussed and reflected on these topics in this interview with him.

What specific needs do wealth management and private banking institutions have?

In addition to seeking technology that empowers advisors, many institutions are expanding their discretionary portfolio management capabilities. This creates demand for technology capable of delivering portfolio construction, execution, and monitoring in a scalable way for large client bases, while maintaining the appropriate levels of personalization and oversight.

What do these institutions value most when selecting a tech provider?

The most important consideration is whether a platform helps advisors deliver more informed and personalized advice, while reinforcing, rather than replacing, the relationship between advisor and client. In markets where private banking is heavily relationship-driven, institutions seek technology that supports more proactive advice, a clearer view of portfolios, and more personalized client interaction at scale. They also demand reliable analytics, risk supervision, and integrated workflows for both advisory and discretionary management, featuring technology that adapts to the systems advisors already use. Increasingly, institutions are also looking for flexibility, transparency, and applicability, including AI capabilities grounded in high-quality data and robust governance frameworks.

What does Aladdin Wealth offer, and why do you think it is one of the most widely used platforms in the market?

Aladdin Wealth is designed to help advisors move from insight to action within a single, connected platform. By integrating data, analytics, portfolio construction, risk supervision, and advisor workflows, it enables institutions to operate from a shared view of the client and their portfolio. The platform brings institutional-grade technology and risk analytics to the wealth management space, helping advisors and discretionary managers handle portfolio complexity more effectively.

What is its key aspect for advisory services?

A key aspect is that Aladdin Wealth supports both advisory and discretionary management business models. As wealth managers seek to scale their management capabilities while preserving a personalized client experience, institutions demand technology capable of connecting investment ideas, model portfolios, execution, and ongoing oversight across the entire value chain. Furthermore, it is important to note that the transformation of wealth management extends beyond traditional private banking. Institutions are seeking technology platforms that can support a broader range of client segments and business models.

Aladdin Wealth offers integrated workflows across various wealth management businesses, supporting private banking, asset managers, mass affluent, and retail banking segments. This helps institutions create a more connected, consistent, and scalable ecosystem for portfolio management, client interaction, and investment decision-making. Instead of devoting resources to maintaining fragmented tech environments, institutions can focus on what sets them apart most: delivering high-quality advice, superior client service, and a more personalized experience.

Where is technology heading in the wealth management and private banking sector?

The sector is moving toward a future where technology, data, and human expertise collaborate to deliver more personalized advice at scale. Technology will play a crucial role by allowing managers to execute their investment ideas, monitor risk, and maintain portfolio oversight, enabling personalization where appropriate. We anticipate that AI and intelligent automation will become increasingly integrated into the advisor’s workflow—from synthesizing portfolio insights and detecting opportunities to supporting client communication and generating investment proposals.

Wealth management firms are shifting from building and maintaining tech infrastructure to using technology as a strategic driver of growth, differentiation, and client service. The winning institutions will be those that combine reliable data, intelligent automation, and human judgment, allowing advisors to deepen client relationships, respond faster to changing market conditions, and deliver more relevant advice in an increasingly complex investment environment.

How is Aladdin Wealth responding to this evolution?

Aladdin Wealth already incorporates AI-based capabilities designed to help advisors work more efficiently and make more informed decisions. However, the effectiveness of these tools will ultimately depend on the quality of the underlying data, the strength of governance frameworks, and the ability to explain analytics in a way that advisors and clients can understand and trust. Importantly, we view AI as an enhancement to the advisor’s capabilities and workflows, never as a replacement. Wealth management is built on personal relationships and trust; AI represents an opportunity to free up advisor time so they can focus on what truly matters.

Underlying Trends in the ETF Industry

  |   By  |  0 Comentarios

Pixabay CC0 Public Domain

The U.S. ETF sector has expanded significantly over recent decades, both in product variety and total volume. According to JPMorgan data, as of late August, there were more than 5,100 ETFs listed in the United States, representing approximately $16.4 trillion in assets under management. "New launches remain robust as providers address new investment themes, offer more granular exposures, expand investment universe coverage, diversify the range of structured outcomes, and continue transferring active management strategies into the ETF wrapper," the firm notes.

Against a backdrop of global growth in exchange-traded funds, JPMorgan highlights four prominent trends currently shaping the global ETF industry:

1. Active ETFs Continue Rapid Expansion

Active products have accounted for more than 60% of new ETF launches in each of the last six years. In the United States, active ETFs now outnumber passive ones, with year-over-year asset growth of around 80%, reaching $1.8 trillion. They are also a key driver for issuers and investors in international markets such as EMEA, where assets under management have roughly doubled year-over-year to $122 billion.

2. Option-Based ETFs Are Booming

Option-based ETFs utilize options contracts (calls and puts) to achieve specific objectives, most commonly income generation (yield) and downside risk mitigation (hedging). Assets in U.S. option-based ETF strategies grew approximately 50% year-over-year to roughly $280 billion (as of mid-May 2026). Covered call funds, which sell call options to generate income, remain the largest segment. However, the fastest growth is occurring in structured outcome ETFs, which aim to deliver payoff profiles similar to structured products.

3. Rise of Leveraged ETFs

Leveraged ETFs, which use debt and financial derivatives to amplify the daily returns of an underlying benchmark index, have also gained popularity. Over the past decade, assets under management (AUM) in U.S.-listed leveraged ETFs have increased nearly sixfold, reaching around $175 billion in equity strategies and over $190 billion across all asset classes (as of mid-May 2026). Growth has been increasingly concentrated in technology-linked exposures, including the Nasdaq, and single-stock leveraged products.

4. Resurgence of Thematic ETFs

Thematic ETFs experienced a major surge early in the pandemic as investor demand grew for exposures tied to innovation and digitalization. Many of these themes subsequently underperformed significantly in late 2021 and throughout 2022 due to market saturation and valuation compression, resulting in a prolonged demand slump. However, they have rebounded over the past year, with themes linked to artificial intelligence development and physical infrastructure buildout attracting substantial capital inflows.

Amerant Recruits Jorge Morasso as Vice President and Wealth Management Advisor

  |   By  |  0 Comentarios

Photo courtesy

Amerant Investments is bolstering its commitment to the Latin American wealth management market with a strategy that extends beyond expanding its product offerings: it is recruiting executives with extensive experience from top U.S. wealth management platforms into its ranks.

The firm, a subsidiary of Amerant Bank, announced the hiring of Jorge Morasso as Vice President and Wealth Management Advisor, following a career of more than 25 years serving high-net-worth international clients, particularly from Latin America. Morasso worked as a financial advisor at Citi and previously spent over a decade at Morgan Stanley.

Based in Coral Gables, Florida, his new responsibilities will focus on serving individuals, families, entrepreneurs, and business owners across Latin America, with specialized expertise in clients connected to Venezuela.

The move carries added significance when viewed alongside another recent key hire. In July, Amerant Investments appointed Ricardo Sucre, who also brings experience from Morgan Stanley, as Head of Business Development for International Wealth Management. Sucre joined with over two decades of experience serving international clients and an explicit mandate to expand the business and attract experienced financial advisors.

Rather than two isolated moves, these hires point toward a platform-building strategy: Amerant seeks to combine the investment capabilities of its broker-dealer with the banking and credit infrastructure of Amerant Bank to compete for a share of Latin American wealth managed from the United States.

The company itself has defined its platform as an integrated model to serve Latin American clients, while its corporate strategy includes selective investments in business development and wealth management talent.

A Florida Bank Focused on Latin American Wealth

The strategic push also has a clear quantitative dimension. Amerant Bancorp closed 2025 with approximately $3.3 billion in assets under management and custody. By the second quarter of 2026, that figure reached $3.37 billion, according to its financial results.

The bank also reported $10.3 billion in total assets and $8.4 billion in deposits at the end of June 2026, demonstrating that the wealth management platform is part of a larger-scale banking operation.

There is another particularly telling detail for the Latin American market: in the first quarter of 2026, Amerant reported approximately $2.006 billion in deposits from clients domiciled in Venezuela, compared to around $705 million from other foreign clients.

This figure explains why Venezuela explicitly features in the firm’s international strategy, even though Amerant’s stated target is regional, encompassing clients throughout Latin America.

Amerant’s move occurs in a market where U.S. financial institutions compete not only to capture assets, but also to recruit advisors who maintain long-standing relationships with Latin American families.

This logic is especially critical in the offshore business, where the advisor serves as the entry point for wealth requiring simultaneous investment, credit, banking, estate planning, and structures across multiple jurisdictions.

In this context, Amerant’s narrative places the integration of banking and investments at the center of its value proposition. The firm offers personalized wealth management and a platform that combines investments, banking, and financial planning, with access to products such as funds, ETFs, fixed income, structured products, and alternatives.

Morasso’s arrival thus reinforces a strategy aimed at more than organic growth; at its core, it seeks to integrate relationships, expertise, and deep understanding of the Latin American client to accelerate the expansion of its international wealth management business.

For Amerant, the challenge will be translating this platform and new talent from major global firms into greater Latin American wealth capture. For established competitors in Miami, the signal is distinct yet equally clear: the international business continues to attract capital—and with it, a renewed battle for the advisors capable of managing it.

State Street Investment Management launches an ETF tracking the UC Endowment Strategy Index

  |   By  |  0 Comentarios

Photo courtesy

State Street Investment Management has announced the launch of the State Street SPDR UC Investments 90/10 Endowment Strategy Index ETF, an asset allocation exchange-traded fund developed in collaboration with UC Investments, the investment division of the University of California and the provider of the fund’s index. The launch is backed by a $2.5 billion seed investment from UC Investments. The ETF has been trading on NYSE Arca since September 1.

The fund aims to track the UC Investments 90/10 Endowment Strategy Index, which combines broad exposure to U.S. equities with exposure to short-duration investment-grade corporate bonds. The index allocates 90% of its weight to the S&P 500 Index and the remaining 10% to the S&P U.S. Investment Grade Corporate Bond 1-3 Year Index, which includes U.S. dollar-denominated, investment-grade corporate bonds with maturities between one and three years.

UC Investments and S&P Dow Jones Indices custom-developed this index, inspired by the institution’s $7.9 billion “Blue and Gold Endowment Pool”—a long-term strategy in public markets that, since its inception seven years ago, has been the top-performing product within UC Investments’ portfolio. The strategy reflects UC Investments’ conviction that low-cost, liquid, and diversified public market exposure can generate attractive long-term returns while avoiding the complexity and illiquidity of traditional endowment models.

By embedding this philosophy into an ETF, UCBG offers long-term investors access to UC Investments’ approach, which was previously only available within the institution’s portfolio and directly to employees across its ten campuses and six medical centers through its retirement savings program—the second-largest public defined contribution program in the nation, behind only the federal government’s.

“At UC Investments, we are focused on building long-term, cost-effective portfolios to support our hundreds of thousands of students, faculty, staff, and alumni for generations to come,” said Jagdeep Singh Bachher, Chief Investment Officer of the University of California. “The launch of this ETF brings our institutional investment philosophy within reach of a broader investor community through the transparency, efficiency, and accessibility of the ETF structure, while staying true to the principles that have guided our investment approach,” he added.

The ETF builds on State Street’s longstanding relationship with UC Investments. State Street Investment Management currently provides asset management services to UC Investments’ portfolio of over $200 billion, spanning pensions, endowments, and other assets, while State Street Bank and Trust Company provides custody and other investment services.

“Our relationship with UC Investments spans more than two decades and has always been driven by innovation. With this launch, we are bringing an endowment-inspired strategy to a much broader range of investors with the low cost and transparency that make ETFs so powerful,” said Ronald O’Hanley, Chairman and CEO of State Street Corporation.

“This collaboration demonstrates what can be achieved when a leading asset owner and asset manager work together to turn a successful institutional investment strategy into an accessible solution for investors,” said Yie-Hsin Hung, President and CEO of State Street Investment Management. “It reflects our commitment to helping clients expand their investment priorities into new markets and investor communities.”

ReachingU Celebrates 25 Years with a Night of Philanthropy, Art, and Reflection in Miami

  |   By  |  0 Comentarios

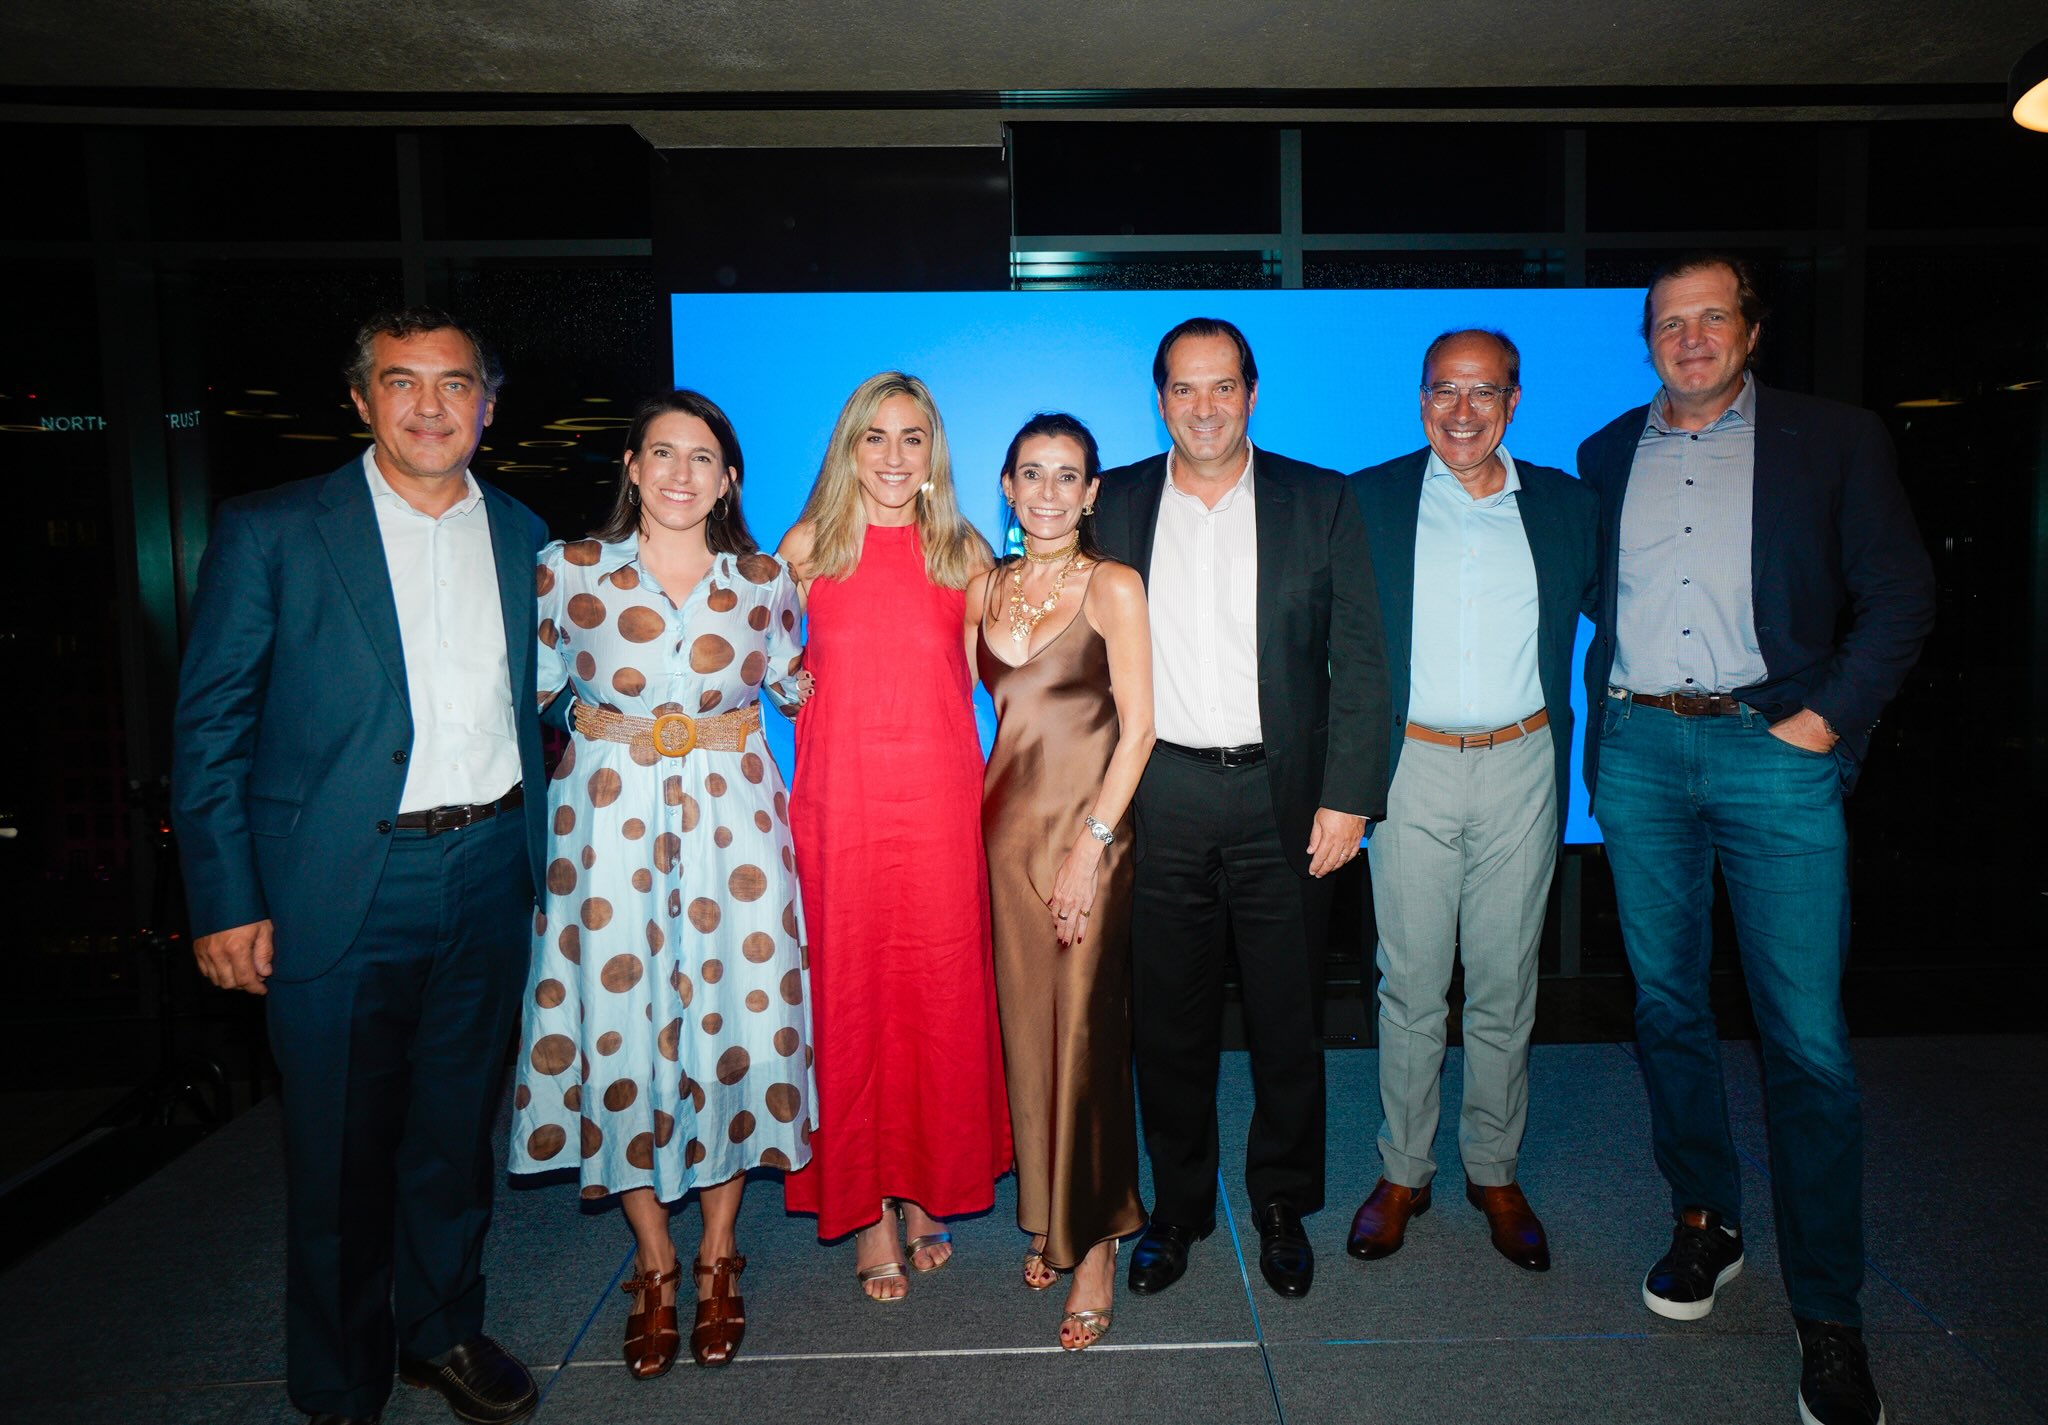
Photo courtesyRepresentatives of the ReachingU Foundation, from Left to Right: Gustavo Civetta, Director; Paula Mosera, Executive Director; Beatriz Ponce de León, Board Chair; Pía Sojo, Director; Nick Stanham, Director; Pablo Haberer, Director; and Ricardo Salmon, Director

Artificial intelligence and education may seem like distant worlds, but they were precisely the two ends of a single conversation during ReachingU’s 25th anniversary celebration dinner in Miami.

The Uruguayan foundation, dedicated to expanding educational opportunities for children and adolescents in the country, brought together members of its community and allies on Wednesday, September 16, at the EAST Miami Hotel for an evening that combined philanthropy, technology, and art.

One of the central themes of the night was the transformation being driven by artificial intelligence. Nicolás Loeff, co-founder and CTO of BrainLogic AI, shared a perspective on the global evolution of this technology and the changes it is generating across various fields.

Another perspective came directly from Uruguayan classrooms. Teacher Pablo Mollo brought a much more concrete reality to the table: the daily challenges of education and the impact of programs aimed at expanding opportunities for students.

The contrast between both perspectives ultimately gave the gathering a significance that extended beyond the anniversary itself. As technology redefines the tools and capabilities available to new generations, educational systems face the challenge of ensuring those opportunities effectively reach children and youth.

The program also featured an artistic component. During the evening, a live auction was held for works donated by artists connected to the foundation. Among the auctioned pieces was “Fuente de Luz,” a sculpture created by Pablo Atchugarry specifically to commemorate ReachingU’s 25 years, alongside a work by Guillermo García Cruz and two silkscreen prints by Daniel Supervielle.

The event featured UBS as the main sponsor and partner of the foundation, while EAST Miami Hotel hosted the evening. Vinos Santa Rosa and Chocolates Haas also participated as event supporters.

Beyond the celebration, fundraising remained the core focus. The resources raised during the night will go toward the educational programs ReachingU develops in Uruguay, which aim to expand opportunities for thousands of children and adolescents.

The anniversary arrives at a time when education faces a dual transformation: on one hand, the accelerated adoption of artificial intelligence tools; on the other, the persistence of gaps that determine who can truly access better educational opportunities.

For ReachingU, the commitment remains firmly at that intersection: turning education into a pathway to expand possibilities for future generations while mobilizing private resources toward that goal from Miami and other international communities.

BNP Paribas AM Implements Its New Organizational Structure to Accelerate Growth and Its 2030 Strategic Plan

  |   By  |  0 Comentarios

Sandro Pierri, Chief Executive Officer of BNP Paribas Asset Management.

BNP Paribas Asset Management has implemented its new organization, an important step in integrating its expanded businesses and executing its 2030 strategic plan. As explained, this new organization is designed to take advantage of the scale and complementary capabilities of its combined platform, driving growth among institutional, insurance, individual, and wealth management clients.

Its objective is to “accelerate the execution of the 2030 strategic plan while enabling BNP Paribas Asset Management (BNP Paribas AM) to fully take advantage of the capabilities of the broader BNP Paribas Group ecosystem.” Consequently, the Alternative Assets business line, led by Isabelle Scemama, Deputy CEO of BNP Paribas AM and Head of BNP Paribas AM Alts, with the support of Deborah Shire, Deputy Head of BNP Paribas AM Alts, maintains its integrated model, which combines investment expertise with dedicated support for each client.

With more than thirty years of experience across various alternative asset classes, including real estate, infrastructure, alternative credit, and private equity, the asset manager considers the business well-positioned to accelerate the ambitions set out in the asset manager’s 2030 strategic plan. Among these are expanding its offer, increasing third-party capital raising, and facilitating greater access to alternative investment solutions.

The Investments business line, led by Rob Gambi, Global Chief Investment Officer, brings together BNP Paribas Asset Management’s capabilities in fixed income, fundamental active equities, multi-asset, and systematic and quantitative investments. As explained, the platform is structured around specialized teams while leveraging greater scale, a broader range of capabilities, and increased research resources. Its objective is to foster the development of solutions that respond to evolving client needs and contribute to achieving the goals set out in the manager’s 2030 strategic plan: expanding the scale of active management and accelerating the development of the company’s ETF and index fund business.

For its part, the Global Client Group Liquid Strategies, led by Steven Billiet, Head of Liquid Strategies at Global Client Group, aims to broaden and deepen relationships with clients investing in BNP Paribas AM’s liquid investment strategy platform. “Leveraging the organization’s greater commercial reach and capabilities, it seeks to strengthen commercial coordination across markets and product lines and accelerate growth in institutional, insurance, retail, and wealth management client segments,” they state.

The business lines are supported by a series of cross-functional support areas, with a stronger focus on Strategic Alliances and Transformation, as well as an evolution of the sustainability model: the Global COO Office, led by Philippe Boulenguiez, Global Chief Operating Officer; the General Secretariat, led by Jean Christophe Ménioux, General Secretary; Human Resources, led by Marion Azuelos, Global Head of Human Resources; Strategic Alliances Office, led by Justyna Dajka, Global Head of Strategic Alliances; and a dedicated Transformation Office, led by Patrick Simion, Head of Transformation, and Communication and Brand, led by Marie Bogataj, Head of Communication and Brand. As noted, the Sustainability organization will evolve and include a cross-functional Sustainability Center, led by Jane Ambachtsheer, Global Head of Sustainability. As part of this reorganization process, BNP Paribas Asset Management has to date formalized the appointment of 200 managers, and new appointments are expected over the coming months.

Executive Committee

Finally, and to “further enhance decision-making efficiency,” the manager is also creating an Executive Committee, responsible for driving strategic direction and priorities. Chaired by Sandro Pierri, it will consist of Isabelle Scemama, Rob Gambi, Steven Billiet, Jean Christophe Ménioux, Marion Azuelos, Philippe Boulenguiez, and Deborah Shire.

“Our strategic plan sets a clear ambition for BNP Paribas Asset Management and defines the areas in which we want to grow. Our new organizational model will allow us to go even further in bringing value to our clients and accelerating the execution of our strategic priorities. It provides us with the scale and capabilities needed to deepen our relationships, leverage the full strength of the BNP Paribas Group, and generate long-term value for our clients,” said Sandro Pierri, CEO of BNP Paribas Asset Management.

On August Inflation and the Fed’s Rate Hike

  |   By  |  0 Comentarios

Pixabay CC0 Public Domain

The advance August inflation figure delivered a negative surprise. Headline CPI came in as expected (+0.4% month-over-month) and remained flat year-over-year at +3.4%. However, core inflation breached the +0.2% mark to reach +0.3%, despite a modest slowdown in year-over-year growth (dropping from 2.5% to 2.4%).

This uptick—driven primarily by mobile phone and communication services, airfares, and lodging—could leak into the August core PCE readings due on the 30th, likely triggering a year-over-year increase of ~+0.3% (up from 0.2% in July).

The postponement of the expected summit between Iran and the Gulf nations—now pushed to Sunday to formulate an alternative transit route through the Strait of Hormuz—alongside new comments from Trump (“Iran is desperate to make a deal quickly”) convey urgency ahead of the upcoming November midterms and shift leverage to Tehran. Consequently, Brent crude rose to $109 per barrel, raising the odds of a prolonged monetary tightening cycle (markets are now pricing in nearly four Fed rate hikes between now and the summer of 2027).

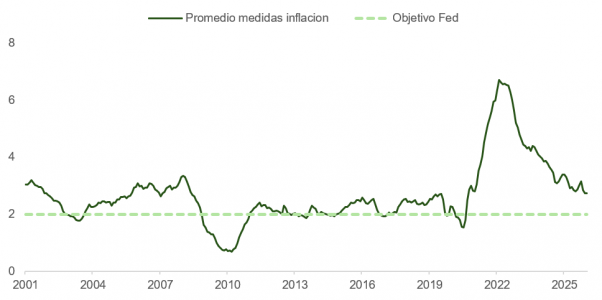
Although the overall trajectory of inflation continues to move closer to the 2% target (as reflected by the average of trimmed-mean, supercore, and sticky inflation metrics), progress has not been as fast as the Federal Reserve’s FOMC would prefer. Adding to these concerns are the price and growth impacts of massive AI investments and strong nominal economic activity, with Atlanta Fed real final sales (which measure total output value adjusted for inflation excluding inventory shifts) holding at three-year highs.

Given this setup, the probability of a 25-basis-point hike (bringing rates to 4%) jumped toward ~90% over the weekend. This presented Kevin Warsh with an opportunity to build market credibility through an insurance hike—one unlikely to derail an economy expanding at nominal growth rates above 7%. Standing pat, by contrast, would have seemed contradictory following his hawkish tone at Jackson Hole.

Warsh entered the decision balancing two forces: accommodating a vocal president or delivering what the bond market was demanding to secure its confidence. While Trump holds immense executive authority, the bond market exerts its own formidable influence on policy.

Warsh opted to raise rates by 25 basis points in a unanimous decision—the first increase since 2023—aiming to guide inflation back toward the 2% target over a reasonable horizon. Statements and the updated dot plot (one additional hike in 2026 priced in for December, a pause through 2027, and cuts starting in 2028) frame this as a mini-cycle of preemptive hikes. The Fed’s upward revision to the terminal rate is supported both by AI-driven productivity gains—a view Warsh strongly champions—and by the continuation of pro-cyclical, expansionary fiscal policies dating back to Trump’s first administration.

Fixed Income Positioning and Key Drivers

Within fixed income, if current inflation forecasts hold, positive surprises are more likely moving forward. With the market having largely priced in the Fed’s stance, a neutral duration posture appears prudent. Close attention should be paid to labor market indicators that could shift the Fed’s path if momentum accelerates, including wage gains among job switchers, shifts in marginally attached workers, hiring demand within AI infrastructure, and jobless claims trends.

The Bank of Japan’s dovish 25-basis-point increase—taking its policy rate to a 30-year high—is another focal point. Higher Japanese yields and increased yen volatility could impact the carry trade, which historically provided funding flows into U.S. fixed income markets.

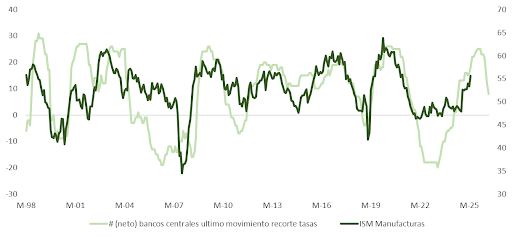
Energy price relief could offer another upside surprise, following news that the Saudi East-West pipeline can resume operation at half capacity immediately, with full repairs slated within six weeks. Meanwhile, central bank activity tracking indicates a clear inflection point away from global monetary easing, suggesting softer industrial momentum entering 2027.

Equities: Impact of the Hike Mini-Cycle on AI

For equity markets, elevated borrowing costs tied to this rate-hike mini-cycle may disproportionately pressure AI companies carrying leveraged balance sheets. Early-stage startups lacking credit ratings—such as specialized neocloud providers—may encounter higher hurdles securing funding for data center builds.

Compounding this are growing public objections to data center construction (Morgan Stanley research indicates 75% of Americans and 83% of Democrats oppose hosting such facilities locally; as a result, $156 billion in projects were delayed or canceled in 2025, followed by another $130 billion in Q1 2026). These constraints could limit total compute supply, benefiting early-moving hyperscalers.

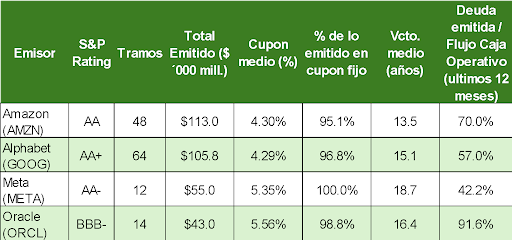
Hyperscalers have secured significant long-term, fixed-rate financing at borrowing costs well below current 10-year Treasury yields, leveraging their investment-grade credit profiles.

Slower deployment of AI capital expenditures—which contributed ~0.6% and ~0.4% to GDP in Q1 and Q2, respectively—could also exert downward pressure on overall inflation readings.

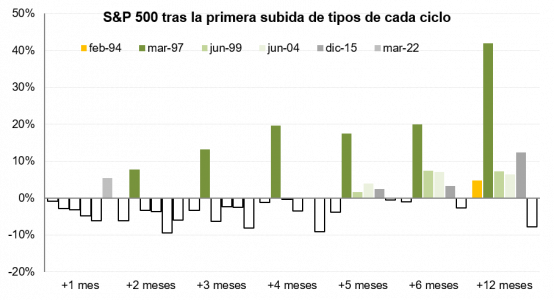
From a historical perspective, analysis of the past six U.S. rate-tightening cycles indicates that while equities often experience short-term volatility following an initial rate hike, broad indexes generally post positive total returns 12 months later. The primary exception remains 2022, when the Fed fell significantly behind the curve.